The information, products and services described on this website are intended solely for persons in Australia who are wholesale clients within the meaning of section 761G of the Corporations Act 2001 (Cth)). They are not directed at, and should not be relied upon by, retail clients.
By clicking Confirm below, you confirm that:
You are a wholesale client for the purposes of section 761G of the Corporations Act 2001 (Cth); and
The market adage of January being the barometer for equity market performance for the year will always get tossed around as investors outline their roadmap for the year ahead particularly coming off the historic events of 2020. The RBA may also be paying particularly close attention to the performance of the US equity market given the strong marriage of the pair since the nadir in risk markets last March. The RBA governor could become a fan of seasonals, with strong statistical evidence that the S&P 500 Index performance for the start of the year drives returns for the remainder of the year. With this in mind, the S&P 500 Index fell -1.11% (for the first month of 2021) in price terms and Deutsche Bank has studied data going back to 1872 that shows negative first months of the year have a strong impact on the performance for the remainder of the year, with 58% resulting in down years.
The RBA will be very disappointed that after embarking on an aggressive QE campaign it has failed to generate the transmission mechanism into the exchange rate that it would of anticipated – an 8% rally since November 2020 would have figured deeply in the surprise move to extend QE by another 100 billion of bonds or 5 billion a week for a further six months. The currency has managed to continue on its ascent with the global liquidity pump switched on full power mode driving a strong performance in commodities markets – with iron ore 22% of our exports – and domestic data surprising to the upside as the fiscal cheque book keeps printing alongside a successful Covid-19 suppression strategy.
The weakness of the USD has also played its part in providing a tailwind for the AUD which will stymie any attempts for the RBA to achieve its overly optimistic target of getting inflation consistently in the 2-3% target band. The RBA is not alone in lamenting the weakness in the USD with the ECB continuing to talk down its currency as USD strength will continue to undermine global economies’ attempts to escape a post-Covid world.
We monitor price action, sentiment and investor positioning as part of our rigorous investment framework and within that there are some subtle signs that indicate that risk markets may be entering a zone where they could pause or correct from their recent moves.
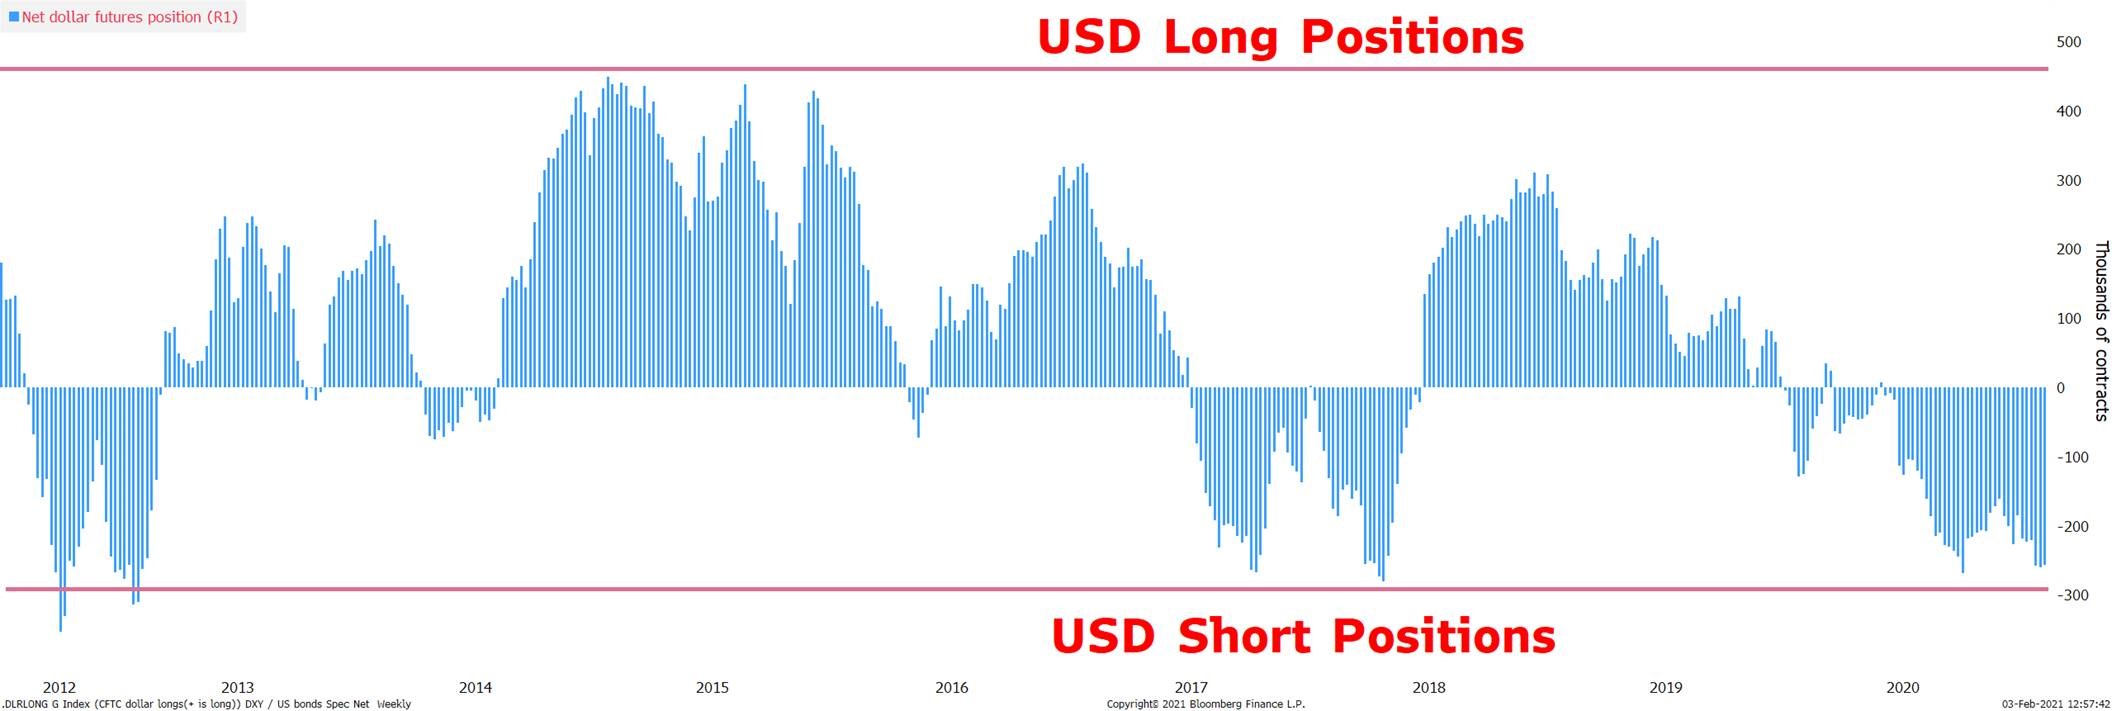
The record short positioning in the USD is a dangerous development with the market all on one side of the boat leaving it very unstable and vulnerable to any unexpected shocks which can generate aggressive unwinding.
The below chart highlights the historically stretched positioning of USD bears which will make it difficult for another secular leg lower in the USD currency as sellers become exhausted.
Source: Bloomberg.
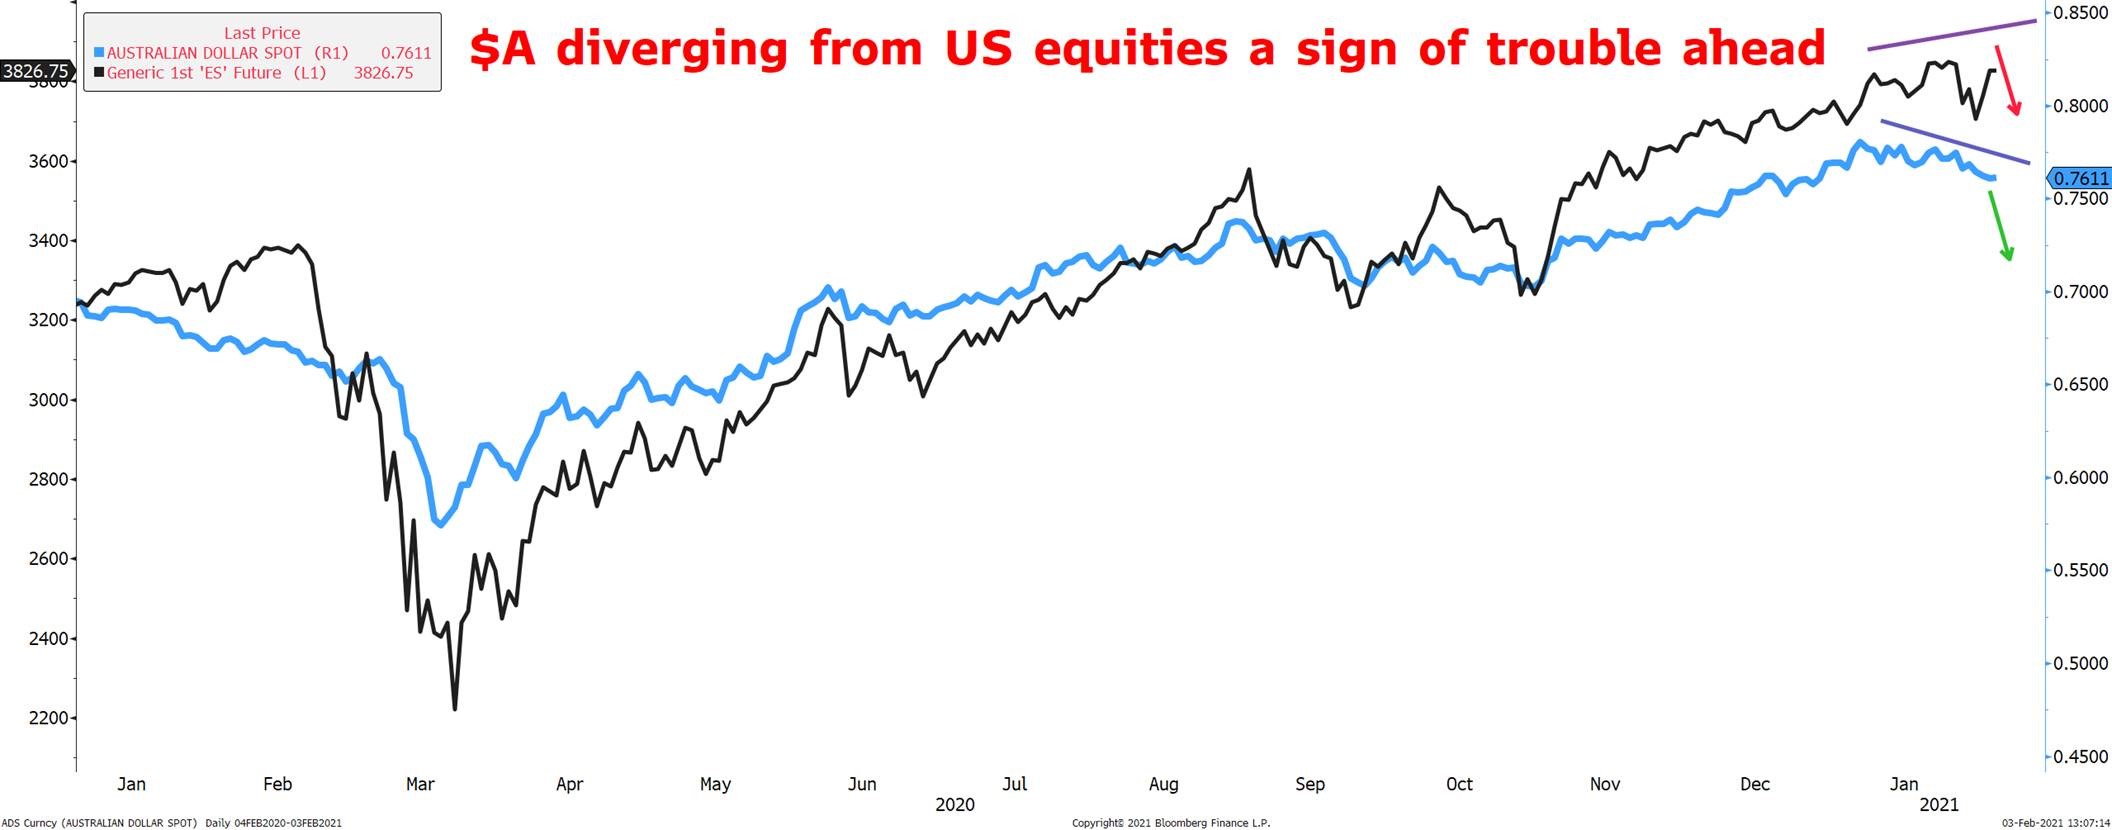
The robust correlation between the AUD and risk markets is well documented and is interesting to note that the price action of late has showed some signs of that marriage starting to sour which provides investors with a salient reminder of the old risk-on/risk-off nature of financial markets and of the possibility that the text-book philosophy of interest-rate differentials may become in vogue again in 2021. The intention of the RBA to weaken the currency with its outsized bond buying program might finally gain some traction if the US/Australian yield differential reasserts its downward trend. Careful what you wish for, as a weaker Australian currency could also suggest trouble lies ahead for risk markets in general.
Source: Bloomberg. Past performance is not indicative of future performance.
This information is for professional and wholesale investors only and has been prepared by JamiesonCooteBonds Pty Ltd ACN 165 890 282 AFSL 459018 (‘JCB’). Channel Investment Management Limited ACN 163 234 240 AFSL 439007 (‘CIML’) is the Responsible Entity and issuer of units for the CC JCB Active Bond Fund ARSN 610 435 302, CC JCB Global Bond Fund ARSN 631 235 553 and the CC JCB Dynamic Alpha Fund ARSN 637 628 918 (collectively ‘the Funds’). Channel Capital Pty Ltd ACN 162 591 568 AR No. 001274413 (‘Channel’) provides investment infrastructure and distribution services for JCB and is the holding company of CIML.
This information is supplied on the following conditions which are expressly accepted and agreed to by each interested party (‘Recipient’). This information contains general financial product advice only and has been prepared without taking into account the objectives, financial situation or needs of any particular person. It is intended solely for wholesale clients (including sophisticated investors) as defined under sections 761G and 761GA of the Corporations Act 2001 (Cth). JCB is not licensed in Australia to provide financial product advice or other financial services to retail investors.
The information provided should not be considered personal advice, a recommendation, or an offer to invest in the Funds. Recipients should not rely on this information in making investment decisions. A Recipient should, before making any investment decisions, consider the appropriateness of the information, and seek professional advice.
Neither JCB, Channel, CIML or their representatives and respective employees or officers (collectively, ‘the Beneficiaries’) make any representation or warranty, express or implied, as to accuracy, reliability or completeness of this information or subsequently provided to the Recipient or its advisers by any of the Beneficiaries, including, without limitation, any historical financial information, the estimates and projections and any other financial information derived there from, and nothing contained in this information is, or shall be relied upon, as a promise or representation, whether as to the past or the future. All investments contain risk. Past performance is not a reliable indicator of future performance.
For further information and before investing, please read the Product Disclosure Statement and Target Market Determination which is available from www.channelcapital.com.au
Thank you for sharing your feedback.
Oops! Something went wrong while submitting the form.
Perspective, not prediction.
Timely views from the investment team on policy, market structure and portfolio construction.