The information, products and services described on this website are intended solely for persons in Australia who are wholesale clients within the meaning of section 761G of the Corporations Act 2001 (Cth)). They are not directed at, and should not be relied upon by, retail clients.
By clicking Confirm below, you confirm that:
You are a wholesale client for the purposes of section 761G of the Corporations Act 2001 (Cth); and
Could a butterfly in China cause a flutter in Germany?
Ben Wang, Assistant Portfolio Manager
While the Evergrande episode continued, Fantasia, a Chinese property developer, missed its $205 million bond repayment on 4 October. The latter is making the headline probably because it is listed in Hong Kong. Many mainland developers, who are not covered by foreign media, are struggling as well. This isn’t a total surprise. We pointed out previously that Evergrande wouldn’t be the only one in trouble given the tightening of Chinese property markets.
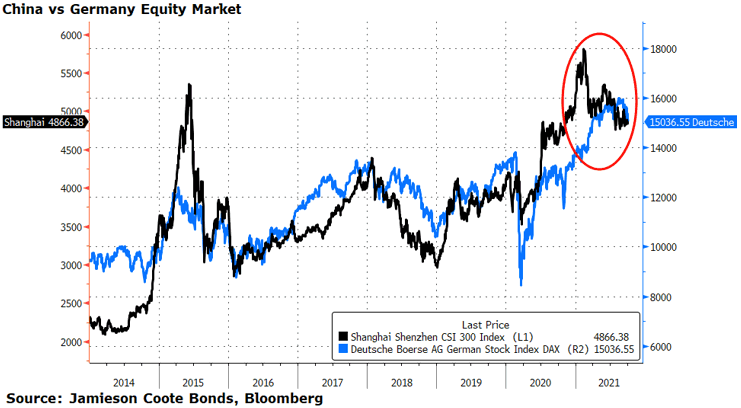
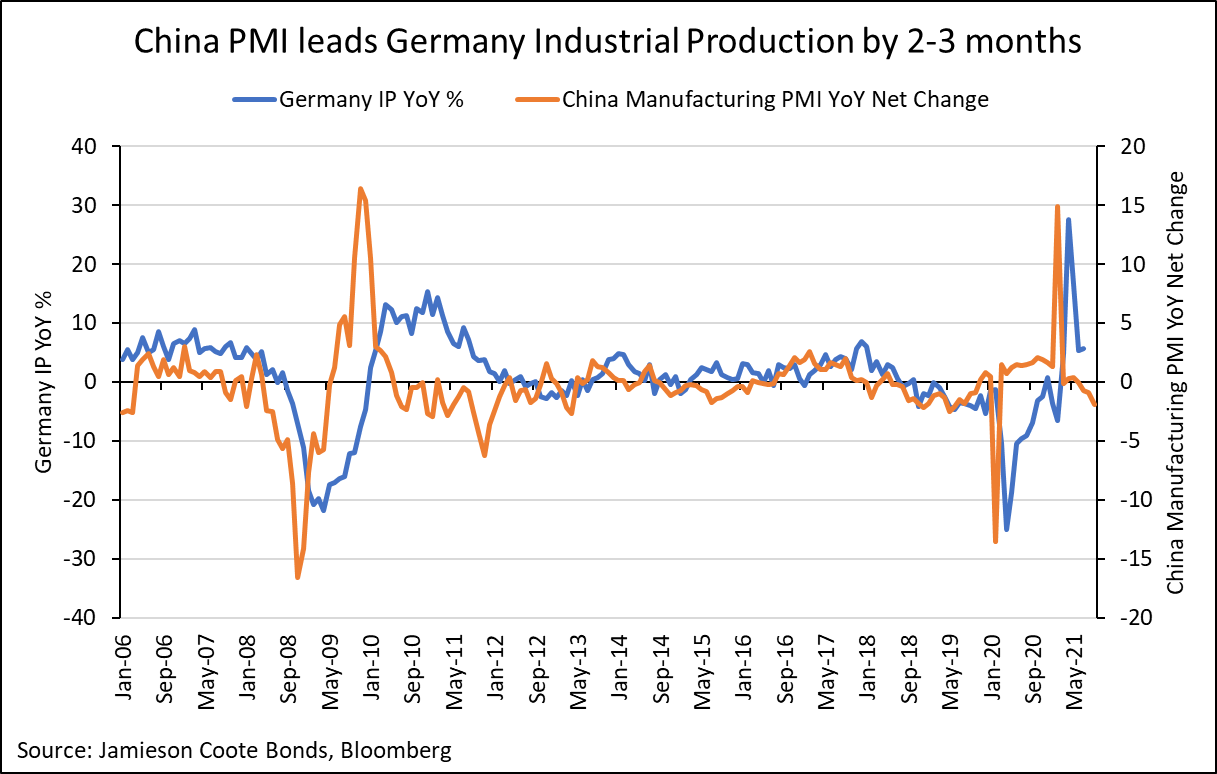
Besides the property market, we notice that another cloud – energy consumption restriction – is emerging in China, which would slow down the Chinese economy further. A storm in China would also be felt in Germany given its close economic ties with China. China PMI leads German industrial production by 2-3 months. The German equity market (represented by the blue line), which has outperformed the Chinese equity market (represented by the black line) YTD 2021, started to converge recently. If the biggest economy in Europe is fluttering due to the Chinese economy slowdown, many other economies could also feel the impact. That makes us cautious on the global economic outlook and the broader growth markets.
Reducing energy consumption may hinder global growth
To reach the “net zero” emission by 2060, the Chinese government has set a target to reduce its national energy consumption versus GDP ratio by 3% in 2021. However, 19 provinces including Guangdong and Jiangsu, the two largest provinces in terms of GDP, are lagging the 2021 target, according to the half-year review released in August. In response, various power cuts and restrictions were implemented to limit factory activities, especially those in high energy-consumption industries.
Considering how energy dependent the world is in so many ways, such draconian measures unsurprisingly have had negative and unintended consequences. On 24 September, 23 workers in a metal factory in the Northeastern China were hospitalised due to gas poisoning. It was caused by a power cut which stopped ventilation systems to expulse of noxious gases. Meanwhile, some cities even cut the power of traffic lights, telecommunication towers and elevators of high-rise residential buildings to help with targets. Moreover, households’ energy consumption is going to rise quickly to keep homes warm and ventilated as the winter is looming. If government sticks to the energy reduction target, the restriction on manufacturing activities likely continues.
These 19 provinces accounted for 70% of China’s industrial production. The power cuts so far have affected 7% of national aluminum production capacity and 29% of cement production. They are estimated to knock off -0.25% GDP in Q3 as these measures intensified in September. If the power restrictions are maintained at the current level, another 0.5%-0.75% GDP could be slashed in Q4. Together with the ongoing property market tightening and the technology crackdown, the Chinese economy is expected to slow down further.
We believe this could also pose a headwind for the German economy in the coming months due to its close economic ties with China. Germany is the largest trading partner of China in Europe. It also has the largest fixed asset investment and the most technology transfers to China among EU members.
On the other hand, China overtook the United States to be Germany’s biggest trading partner in 2020 and became a major market of German companies. Mercedes-Benz delivered three times as many cars to China in the first half of 2021, as it did to the United States. The strong economic relationship is evidenced by the fact that the Chinese economy leads the Germany economy by 2-3 months historically. The economic headwind from the Chinese economy would be felt in Germany soon. The recent convergence of the German equity market to Chinese equity market may partly reflect this macro trend.
China has become a top trading partner for over 120 countries and regions including the United States and Japan. The economic headwind from China could reach beyond Germany. As investors, this makes us cautious on the global economic outlook and the broader growth of markets as we head into 2022.
This information is for professional and wholesale investors only and has been prepared by JamiesonCooteBonds Pty Ltd ACN 165 890 282 AFSL 459018 (‘JCB’). Channel Investment Management Limited ACN 163 234 240 AFSL 439007 (‘CIML’) is the Responsible Entity and issuer of units for the CC JCB Active Bond Fund ARSN 610 435 302, CC JCB Global Bond Fund ARSN 631 235 553 and the CC JCB Dynamic Alpha Fund ARSN 637 628 918 (collectively ‘the Funds’). Channel Capital Pty Ltd ACN 162 591 568 AR No. 001274413 (‘Channel’) provides investment infrastructure and distribution services for JCB and is the holding company of CIML.
This information is supplied on the following conditions which are expressly accepted and agreed to by each interested party (‘Recipient’). This information contains general financial product advice only and has been prepared without taking into account the objectives, financial situation or needs of any particular person. It is intended solely for wholesale clients (including sophisticated investors) as defined under sections 761G and 761GA of the Corporations Act 2001 (Cth). JCB is not licensed in Australia to provide financial product advice or other financial services to retail investors.
The information provided should not be considered personal advice, a recommendation, or an offer to invest in the Funds. Recipients should not rely on this information in making investment decisions. A Recipient should, before making any investment decisions, consider the appropriateness of the information, and seek professional advice.
Neither JCB, Channel, CIML or their representatives and respective employees or officers (collectively, ‘the Beneficiaries’) make any representation or warranty, express or implied, as to accuracy, reliability or completeness of this information or subsequently provided to the Recipient or its advisers by any of the Beneficiaries, including, without limitation, any historical financial information, the estimates and projections and any other financial information derived there from, and nothing contained in this information is, or shall be relied upon, as a promise or representation, whether as to the past or the future. All investments contain risk. Past performance is not a reliable indicator of future performance.
For further information and before investing, please read the Product Disclosure Statement and Target Market Determination which is available from www.channelcapital.com.au
Thank you for sharing your feedback.
Oops! Something went wrong while submitting the form.
Perspective, not prediction.
Timely views from the investment team on policy, market structure and portfolio construction.