The information, products and services described on this website are intended solely for persons in Australia who are wholesale clients within the meaning of section 761G of the Corporations Act 2001 (Cth)). They are not directed at, and should not be relied upon by, retail clients.
By clicking Confirm below, you confirm that:
You are a wholesale client for the purposes of section 761G of the Corporations Act 2001 (Cth); and
Decade of Excellence: 10 year journey in Government Bonds
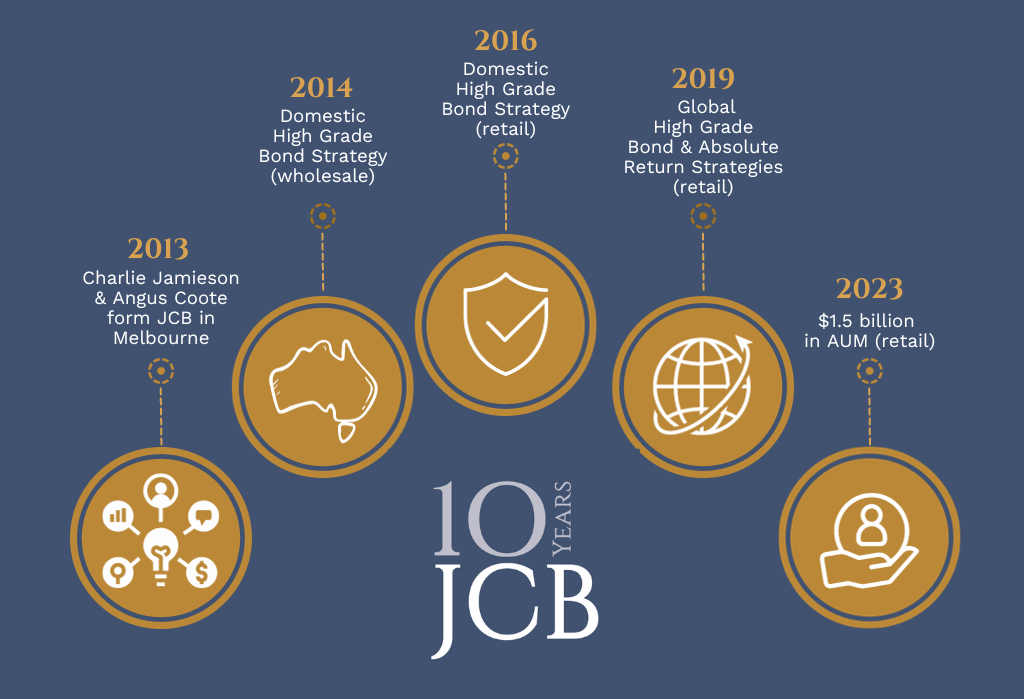
Throughout the past decade, Jamieson Coote Bonds has consistently displayed a firm dedication and expertise in effectively managing government bonds. This journey began in the heart of Melbourne's financial district, where the firm was founded by its co-founders, Charlie Jamieson and Angus Coote.
Driven by a shared vision to provide Australian investors with genuinely defensive investment opportunities, Jamieson Coote Bonds has evolved into an institutionally recognised investment management firm. Through expanding its investment team strength and diversifying its investment solutions, the firm currently oversees $A1.5 billion (as at 31 July 2023) on behalf retail investors.
Effectively managing bond portfolios through the full economic cycle
Jamieson Coote Bonds’ experience extends far beyond the last decade, having effectively managed bond portfolios during economic expansions, contractions, and periods of recovery. With a dedicated focus on high grade bond management, the investment team actively positions investments in government bonds, adjusting duration and yield considerations in response to shifting economic conditions, and monitoring interest rate movements and inflationary pressures. Successful management also entails diversifying within the government bond universe, which may include bonds issued by various Australian and G7 government entities and maturities. The goal is to maximise returns while minimising risk exposure, ensuring that the portfolio remains resilient across the cycle.
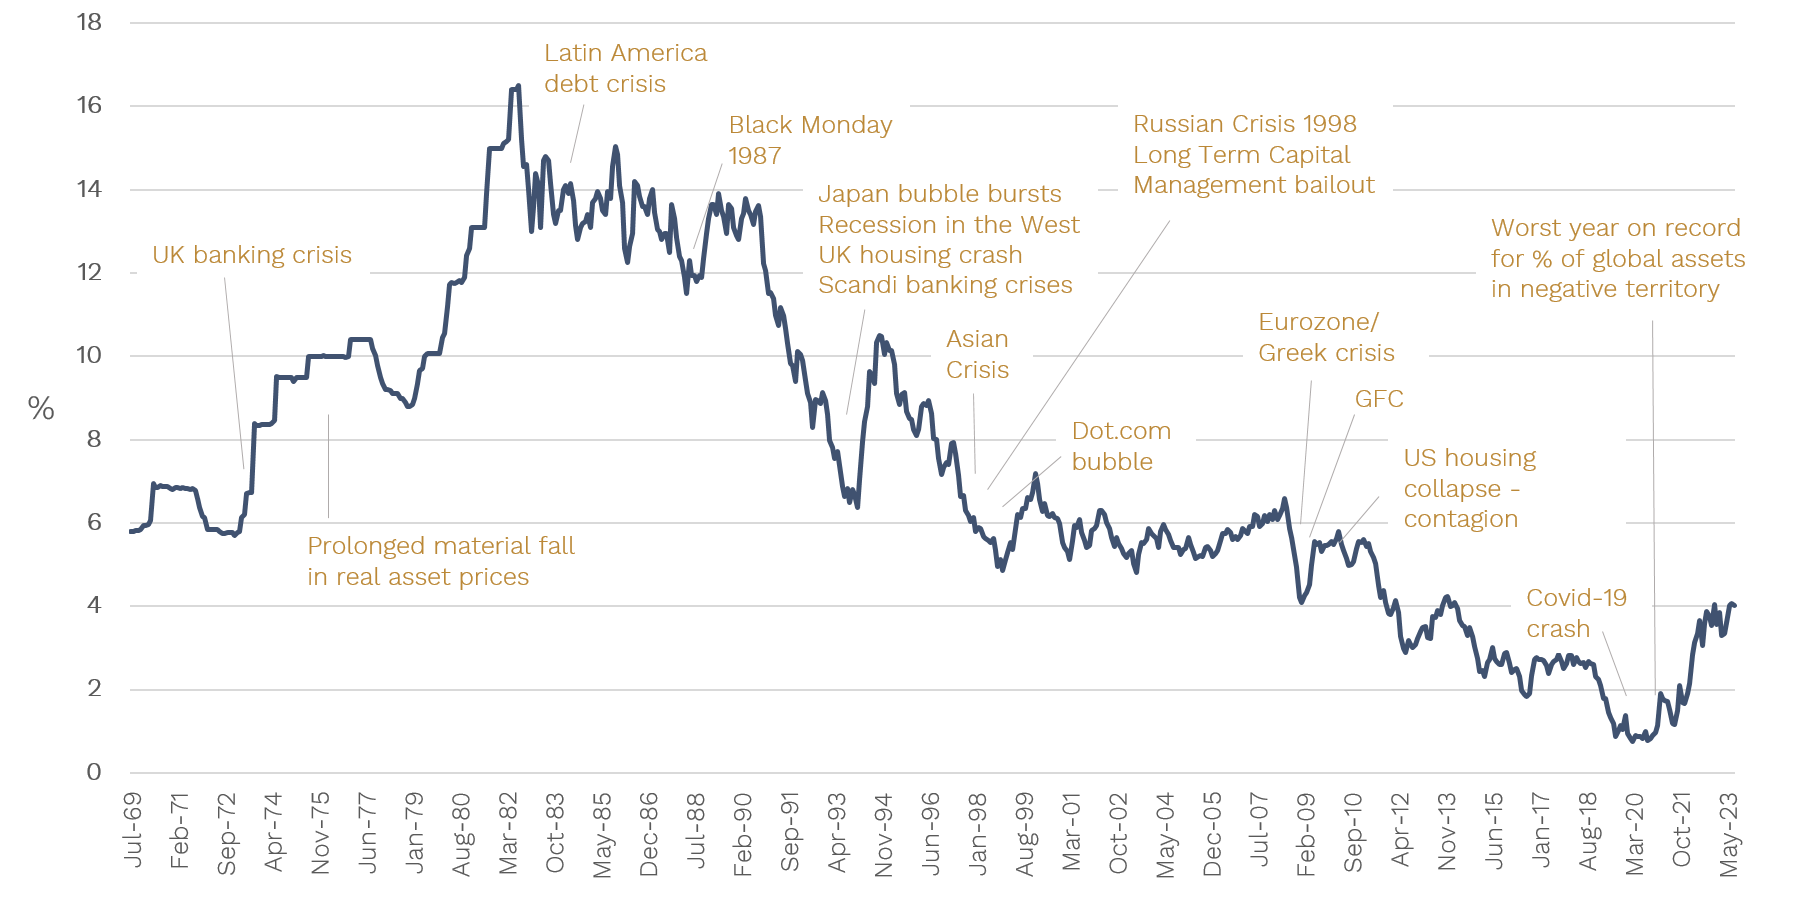
Australian Commonwealth Government Bonds – 10 year yields %
Bond yields are influenced by various factors, including changes in monetary policy, economic conditions, and global financial events.
Source: RBA, Bloomberg
Rethinking fixed income
The Global Financial Crisis (GFC) in 2008 had a transformative effect on government bond markets globally. Many governments implemented fiscal stimulus measures and rescue packages which were financed by issuing government bonds. This increased issuance expanded the size of government bond markets in many countries, making them larger and more liquid.
As a result, government bonds assumed an even greater role as safe-haven assets, particularly during times of volatility and uncertainty. Investors began to recognise the benefits of asset specialisation, specifically segregating fixed income assets to construct portfolios focused on both defensive positioning and income generation.
Reflecting on the past 10 years, Angus Coote, co-founder, said,
“It has been an incredible journey. We are proud of what we have achieved as a business and for our investors, but we are also mindful of the challenges ahead. Fixed income markets are constantly evolving, and we aim to continue delivering value to our investors.”
In addition, the conventional strategy of relying on a composite fixed income approach or adopting a one size fits all fixed income allocation, as guided by a composite benchmark, was one that no longer aligned with investor objectives. A composite allocation typically combines a mix of high-yield bonds (often known as junk bonds), corporate bonds, and government bonds, and each carry their unique set of risks.
Jamieson Coote Bonds was formed to provide investors with this optionality. By allowing for the separation of liquid and high quality sovereign bonds to be separated out from credit securities exposure within fixed income portfolios. Jamieson Coote Bonds believes that allocating to specialist managers within fixed income sub-sectors can allow investors to better achieve their objectives.
Liquidity: more than a commodity, it's a precious asset
As a trusted investment manager, Jamieson Coote Bonds has made good on its promise to defend and protect – in good times and bad. Using the experience of the pandemic of 2020 as an example, high quality fixed income assets performed extremely well, rallying strongly while many other asset classes suffered under intense uncertainty. Australian equities, for instance, experienced a nearly 40% pullback at one point. During this period, investors were able to capitalise on their fixed income holdings by selling at a profit and strategically transitioning into undervalued equities, reaping substantial profits. During this period of market stress, Jamieson Coote Bonds did not implement any exit restrictions on its investors, a contrast to many other fixed income asset managers. This serves as a prime example of how a defensive strategy is designed to operate effectively.
The changing bond market
In mid-August of this year, the yield on the benchmark 10-year Treasury note reached its highest levels since 2007. At the same time, an inverted yield curve persists, meaning certain shorter-term securities offer higher yields than some longer-term instruments. Nevertheless, this may be a time for investors to consider positioning fixed income portfolios to capture upside potential further out on the maturity spectrum. The inverse relationship between bond yields and bond prices presents a challenge for existing bondholders when yields are on the rise. When yields rise, prices of current bond issues fall, a function of supply and demand. When demand for bonds declines, issuers of new bonds must offer higher yields to attract buyers, reducing the value of lower-yielding bonds already on the market.
What are the best options for bond investors in today’s market?
Presently, there are more appealing opportunities due to the increased yields available. Investors with existing bond portfolios should contemplate extending their investments towards longer maturities, where they can secure reasonably attractive yields over an extended period. It's noteworthy that, despite shorter-term securities offering higher yields, longer-term bonds have delivered comparable total returns during the first half of 2023.
Jamieson Coote Bonds believes investors can benefit from positioning their fixed income portfolios with longer duration bonds that are more in line with their long-term goals and time horizon.
Opting to allocate a larger portion of one's bond holdings to high quality segments of the fixed income market can yield broader diversification advantages. It is a way to add diversification to help manage risks in a portfolio that includes equities, which tend to experience more short-term volatility. In 2022, an unusual event unfolded as both equities and bonds saw a decrease in their value. However, when considering the long-term perspective, holding high grade bonds will typically help smooth volatility in an investor’s diversified portfolio.
As is often the case in the late cycle environment we find ourselves in today, any geopolitical or global policy changes can trigger market reactions − the Jamieson Coote Bonds investment team is prepared to skilfully manage these risks on behalf of investors.
Jamieson Coote Bonds offers investors a selection of three distinct government bond solutions.
Domestic High Grade Bond Fund - CC JCB Active Bond Fund: Domestic government bond strategy providing superior liquidity and credit quality.
Global High Grade Bond Fund - CC JCB Global Bond Fund: Global government bond strategy providing diversification through exposure to G7 Governments.
Global Absolute Return Fund - CC JCB Dynamic Alpha Fund: A global absolute return government bond strategy, providing uncorrelated returns to traditional fixed income market benchmarks and risk assets.
This information is for professional and wholesale investors only and has been prepared by JamiesonCooteBonds Pty Ltd ACN 165 890 282 AFSL 459018 (‘JCB’). Channel Investment Management Limited ACN 163 234 240 AFSL 439007 (‘CIML’) is the Responsible Entity and issuer of units for the CC JCB Active Bond Fund ARSN 610 435 302, CC JCB Global Bond Fund ARSN 631 235 553 and the CC JCB Dynamic Alpha Fund ARSN 637 628 918 (collectively ‘the Funds’). Channel Capital Pty Ltd ACN 162 591 568 AR No. 001274413 (‘Channel’) provides investment infrastructure and distribution services for JCB and is the holding company of CIML.
This information is supplied on the following conditions which are expressly accepted and agreed to by each interested party (‘Recipient’). This information contains general financial product advice only and has been prepared without taking into account the objectives, financial situation or needs of any particular person. It is intended solely for wholesale clients (including sophisticated investors) as defined under sections 761G and 761GA of the Corporations Act 2001 (Cth). JCB is not licensed in Australia to provide financial product advice or other financial services to retail investors.
The information provided should not be considered personal advice, a recommendation, or an offer to invest in the Funds. Recipients should not rely on this information in making investment decisions. A Recipient should, before making any investment decisions, consider the appropriateness of the information, and seek professional advice.
Neither JCB, Channel, CIML or their representatives and respective employees or officers (collectively, ‘the Beneficiaries’) make any representation or warranty, express or implied, as to accuracy, reliability or completeness of this information or subsequently provided to the Recipient or its advisers by any of the Beneficiaries, including, without limitation, any historical financial information, the estimates and projections and any other financial information derived there from, and nothing contained in this information is, or shall be relied upon, as a promise or representation, whether as to the past or the future. All investments contain risk. Past performance is not a reliable indicator of future performance.
For further information and before investing, please read the Product Disclosure Statement and Target Market Determination which is available from www.channelcapital.com.au
Thank you for sharing your feedback.
Oops! Something went wrong while submitting the form.
Perspective, not prediction.
Timely views from the investment team on policy, market structure and portfolio construction.