The information, products and services described on this website are intended solely for persons in Australia who are wholesale clients within the meaning of section 761G of the Corporations Act 2001 (Cth)). They are not directed at, and should not be relied upon by, retail clients.
By clicking Confirm below, you confirm that:
You are a wholesale client for the purposes of section 761G of the Corporations Act 2001 (Cth); and
Global economies and financial markets are now entering the late stages of the business cycle. Fiscal stimulus has peaked and household purchasing power from savings and earnings is being eroded by the higher inflation backdrop. As we look at the powerhouse of the global economy, the U.S Gross Domestic Product (GDP) growth in 2022 is still projected at 3.5%, materially above the 2.2% average of the last cycle. With anticipated downward revision of the U.S growth trajectory possible in the near future, this could trigger the re-evaluation of the investors blend of growth versus defensive assets.
Fiscal impulse is fading
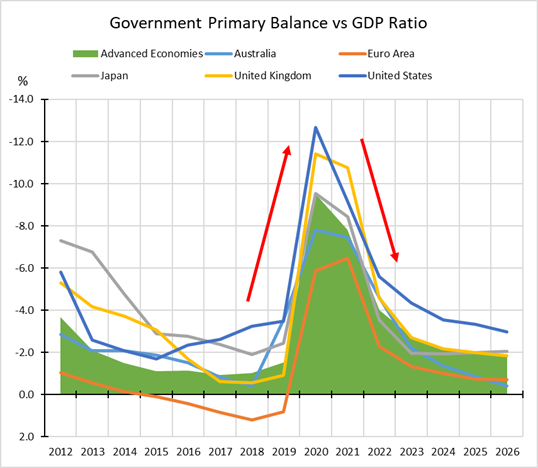
The COVID-19 pandemic shocked the global economy. Cities were locked down, businesses were closed, and millions of workers lost their jobs as consumer confidence took a battering. This was the most severe economic contraction since WWII, which triggered the largest fiscal stimulus package the world has ever witnessed. According to data from the International Monetary Fund (IMF), the U.S government’s primary balance vs GDP ratio, which measures the fiscal net expenditure excluding interest payments, went from -3.5% in 2019 to -12.7% in 2020 (figure 1). Even the governments in the Euro Area, who had a positive primary balance to repair their balance sheets after the European Crisis, ended the austerity and increased fiscal spending significantly to combat the effected slowdown caused by the pandemic.
Source: IMF, JCB
The largesse of authorities mitigated the pandemic impact on consumption and output. Wage subsidies, transfers, and jobless benefits protected jobs and supported household income, which helped consumer spending get through this period. Governments also offered credit support to prevent corporates from bankruptcy, which avoided any contagion developing through the financial community. Economists from the Federal Reserve, University of Cambridge, and IMF estimated that the financial support boosted the GDP of advanced economies by 6.9% in 2020 Q2 and Q3*.
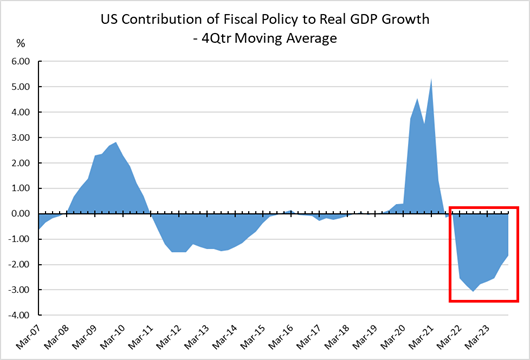
As the economy recovered, governments rightfully scaled back the stimulus that was required. The IMF expects the primary deficits to shrink rapidly from 2022 onwards. The unwinding of the fiscal stimulus means that its impact on the economic growth will turn from a booster to a drag. According to the Hutchins Center at the Brookings Institute, the 4-quarter average of U.S fiscal contribution to GDP peaked at +5.4% in 2021 Q1.
The fiscal impulse fell over the cliff and turned negative in 2021 Q3 – two quarters later. Subsequently it would drop further to -3.1% in 2022 Q3**. This estimation would be revised up significantly if the Biden administration could pass the multi-trillion-dollar Build-Back-Better bill. However high inflation makes further stimulus unpopular among voters who are already sacrificing more consumption dollars with the uplift in energy prices. Given the political gridlock in Washington D.C and the approaching mid-term elections, passing that bill is still possible but not probable.
Source: Hutchins Center at Brookings Institute, JCB.
Consumption vs inflation
US GDP is projected to grow at 3.5% in 2022 vs 5.7% in 2021 despite the fading fiscal impulse. The key assumption behind the optimistic outlook is that excess savings from fiscal stimulus, wealth effects and solid wage growth would keep demand strong. Specifically, the fiscal drag would be offset by a further reopening of the service sector, pent-up demand for goods that were in short supply in 2021, and inventories restoking towards pre-Covid levels. Private consumption is expected to contribute 2.4% out of the 3.5% total GDP growth.
High inflation is a clear threat to these forecasts. It erodes the real value of the saving and wealth whilst also diminishing the purchasing power of the consumers income. Despite the fact that the U.S nominal hourly earnings grew at a respectable 5.1% year on year (YoY) in February, consumers can afford less goods and services than 12-months ago due to much higher inflation rate which was 7.9% YoY.
In addition, the current conflict between Russia and Ukraine makes the consumption outlook even worse. From when Russia began the large-scale invasion on 24 February to the time of writing (28 March), West Texas Intermediate (WTI) crude oil increased +19% and wheat price lifted by +23%. When consumers are spending more on the basics like food and gasoline, they simply have less disposable income for other products and services. If the U.S gasoline price remains elevated at the current price, more than 1% of GDP growth would be cut off.
Overall, fiscal stimulus has peaked and households' purchasing power from savings and earnings is being eroded by the high inflation. The US GDP growth in 2022 is still projected at 3.5%, way above the 2.2% average of the last cycle. Jamieson Coote Bonds is cautious about the optimistic growth outlook. Due to the headwinds, the more downward revision of the growth trajectory might be down the road, which could trigger the re-evaluation of growth and defensive assets.
This information is for professional and wholesale investors only and has been prepared by JamiesonCooteBonds Pty Ltd ACN 165 890 282 AFSL 459018 (‘JCB’). Channel Investment Management Limited ACN 163 234 240 AFSL 439007 (‘CIML’) is the Responsible Entity and issuer of units for the CC JCB Active Bond Fund ARSN 610 435 302, CC JCB Global Bond Fund ARSN 631 235 553 and the CC JCB Dynamic Alpha Fund ARSN 637 628 918 (collectively ‘the Funds’). Channel Capital Pty Ltd ACN 162 591 568 AR No. 001274413 (‘Channel’) provides investment infrastructure and distribution services for JCB and is the holding company of CIML.
This information is supplied on the following conditions which are expressly accepted and agreed to by each interested party (‘Recipient’). This information contains general financial product advice only and has been prepared without taking into account the objectives, financial situation or needs of any particular person. It is intended solely for wholesale clients (including sophisticated investors) as defined under sections 761G and 761GA of the Corporations Act 2001 (Cth). JCB is not licensed in Australia to provide financial product advice or other financial services to retail investors.
The information provided should not be considered personal advice, a recommendation, or an offer to invest in the Funds. Recipients should not rely on this information in making investment decisions. A Recipient should, before making any investment decisions, consider the appropriateness of the information, and seek professional advice.
Neither JCB, Channel, CIML or their representatives and respective employees or officers (collectively, ‘the Beneficiaries’) make any representation or warranty, express or implied, as to accuracy, reliability or completeness of this information or subsequently provided to the Recipient or its advisers by any of the Beneficiaries, including, without limitation, any historical financial information, the estimates and projections and any other financial information derived there from, and nothing contained in this information is, or shall be relied upon, as a promise or representation, whether as to the past or the future. All investments contain risk. Past performance is not a reliable indicator of future performance.
For further information and before investing, please read the Product Disclosure Statement and Target Market Determination which is available from www.channelcapital.com.au
Thank you for sharing your feedback.
Oops! Something went wrong while submitting the form.
Perspective, not prediction.
Timely views from the investment team on policy, market structure and portfolio construction.