The information, products and services described on this website are intended solely for persons in Australia who are wholesale clients within the meaning of section 761G of the Corporations Act 2001 (Cth)). They are not directed at, and should not be relied upon by, retail clients.
By clicking Confirm below, you confirm that:
You are a wholesale client for the purposes of section 761G of the Corporations Act 2001 (Cth); and
Part 2: Unconventional monetary policy: Japan and Germany's experience
The Japanese and German approaches to unconventional monetary policies have not always produced the outcome central banks desired.
Japan and Germany are two nations that have used unconventional monetary policies to stimulate economic growth, albeit for different reasons and under different circumstances. Here, the second article in a three-part series on unconventional monetary policies, we explore the backdrop to the decision by these countries to embark on zero and negative interest rates and quantitative easing.
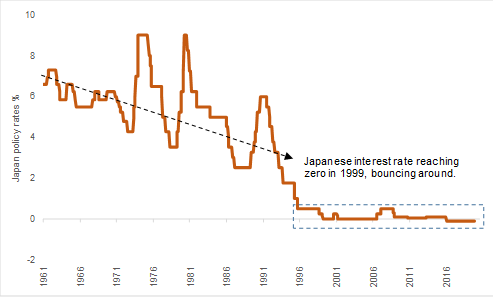
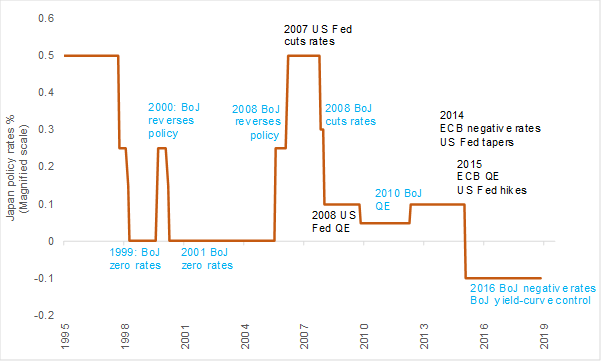
Japan has had a number of forays into zero interest rates. One was in February 1999 and it embarked on another round two years later in response to the dot.com bubble bursting. In addition to moving into negative interest rates, in 2001 the country also pursued a program of quantitative easing. This lasted until July 2006 when the Bank of Japan (BoJ) began to normalise rates. A decade later in January 2016, the BoJ again adopted negative rates, mostly to prevent an unwelcome strengthening of the yen from hurting the export-reliant economy.
When the BoJ first introduced unconventional monetary policies, its approach was viewed to be extreme and isolated to Japan. But only a few years later thanks to the financial crisis of 2007 and 2008, the US Federal Reserve (the Fed) and the European Central Bank (ECB) took a similar approach.
Chart 1: Japanese interest rates – 1961 to 2019
Source: JCB team analysis based on data from Bloomberg.
Chart 2: Japanese interest rate policies – 1995 to 2019
Source: JCB team analysis based on data from Bloomberg.
The response to unconventional monetary policy
The BoJ’s accommodative monetary policies were designed to stimulate economic growth. But instead, they prompted a number of unexpected outcomes.
Japanese households ignored the easy money and ended up saving more and spending less. This suppressed demand, which added to the country’s economic troubles. Concurrently, a credit crunch emerged as the Japanese banks’ bad and doubtful debt exposures accumulated. Small, medium and even some large-sized businesses were unable to repay their loans.
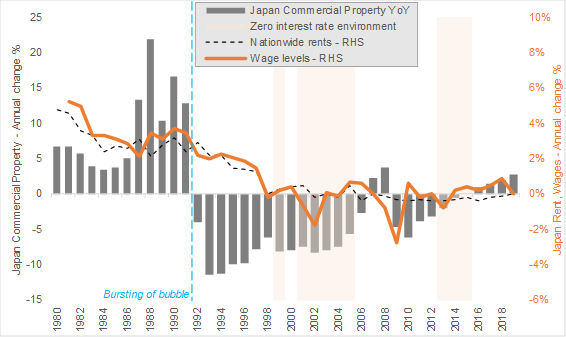
The property market played a key role in the economy as this situation played out. The frothy commercial property market that was one of the main features of the Japanese market in the 1980s and ‘90s suffered immensely in the crash. It has never fully returned to pre-boom levels.
Chart 3: Japan − the bubble bursting led to poor outcomes across rents, wages and property.
Source: JCB team analysis based on data from Bloomberg.
As chart above shows, from 1991 the commercial property sector endured fourteen consecutive years of falling valuations, a trend that challenged the notion property investments are safe and accretive. Simultaneously, rental levels plummeted as economic activity remained anaemic. Property owners who had enjoyed double-digit yields at the peak of the bubble subsequently saw the value of their property drop below the value of their outstanding debt.
Meanwhile, low growth and deflationary pressures weighed on the Japanese sharemarket. Equities reached historic lows in 1989 and the market subsequently saw a number of false dawns. This was because corporates focused on restructuring balance sheets and paying down debt rather than growing their enterprises through borrowing at highly attractive interest rates.
Germany’s experience
Germany is another country where unconventional monetary policies have been used to try to reboot a lacklustre economy.
Its industries have been weighed down by China’s economic rebalancing, the global trade war and evolving consumer trends. Investment spending has receded, the labour market is tepid and business and consumer confidence is soft. Additionally, the aging demographic acts as an anchor on productivity growth and contributes to banking sector weaknesses. On top of this, weak lending, high operating cost bases and poor profitability in the face of low interest rates are acting as handbrakes on economic output.
Germany’s monetary policy is decided by the European Central Bank (ECB). In 2012 it introduced zero interest rates, followed by negative interest rates of -0.1% from June 2014. While these measures were viewed as extreme, credit growth had been stagnant and the central bank wanted to encourage lending to make it punitive for banks to store excess cash. Nevertheless, German and other northern European region banks still store close to €1.25 trillion in excess reserves. So money has not flowed freely across the economy, adding to the malaise.
Unconventional monetary policies have caused European share markets to rally, although financial sector stocks have not performed as well as defensive shares. Overall, however, the economy remains soft and policymakers continue to explore all options to support economic activity.
In the next instalment of this three-part series we’ll explore lessons from Japan’s and Germany’s use of unconventional monetary policies.
Subscribe for more insights like this or call 1800 940 599.
This information is provided by JamiesonCooteBonds Pty Ltd ACN 165 890 282 AFSL 459018 (‘JCB’). This information has been prepared for the purposes of providing general information and should not be considered advice or a recommendation to investors or potential investors in relation to holding, purchasing or selling units and/or investments and does not take into account your particular investment objectives, financial situation or needs. Past performance is not a reliable indicator of future performance. All investments contain risk. Before acting on any information you should consider the appropriateness of the information having regard to these matters, any relevant offer document and in particular, you should seek independent financial advice.
This information is for professional and wholesale investors only and has been prepared by JamiesonCooteBonds Pty Ltd ACN 165 890 282 AFSL 459018 (‘JCB’). Channel Investment Management Limited ACN 163 234 240 AFSL 439007 (‘CIML’) is the Responsible Entity and issuer of units for the CC JCB Active Bond Fund ARSN 610 435 302, CC JCB Global Bond Fund ARSN 631 235 553 and the CC JCB Dynamic Alpha Fund ARSN 637 628 918 (collectively ‘the Funds’). Channel Capital Pty Ltd ACN 162 591 568 AR No. 001274413 (‘Channel’) provides investment infrastructure and distribution services for JCB and is the holding company of CIML.
This information is supplied on the following conditions which are expressly accepted and agreed to by each interested party (‘Recipient’). This information contains general financial product advice only and has been prepared without taking into account the objectives, financial situation or needs of any particular person. It is intended solely for wholesale clients (including sophisticated investors) as defined under sections 761G and 761GA of the Corporations Act 2001 (Cth). JCB is not licensed in Australia to provide financial product advice or other financial services to retail investors.
The information provided should not be considered personal advice, a recommendation, or an offer to invest in the Funds. Recipients should not rely on this information in making investment decisions. A Recipient should, before making any investment decisions, consider the appropriateness of the information, and seek professional advice.
Neither JCB, Channel, CIML or their representatives and respective employees or officers (collectively, ‘the Beneficiaries’) make any representation or warranty, express or implied, as to accuracy, reliability or completeness of this information or subsequently provided to the Recipient or its advisers by any of the Beneficiaries, including, without limitation, any historical financial information, the estimates and projections and any other financial information derived there from, and nothing contained in this information is, or shall be relied upon, as a promise or representation, whether as to the past or the future. All investments contain risk. Past performance is not a reliable indicator of future performance.
For further information and before investing, please read the Product Disclosure Statement and Target Market Determination which is available from www.channelcapital.com.au
Thank you for sharing your feedback.
Oops! Something went wrong while submitting the form.
Perspective, not prediction.
Timely views from the investment team on policy, market structure and portfolio construction.