The information, products and services described on this website are intended solely for persons in Australia who are wholesale clients within the meaning of section 761G of the Corporations Act 2001 (Cth)). They are not directed at, and should not be relied upon by, retail clients.
By clicking Confirm below, you confirm that:
You are a wholesale client for the purposes of section 761G of the Corporations Act 2001 (Cth); and
Part 3: Lessons for investors from unconventional monetary policy
Sovereign bonds have the potential to support investor returns during periods when countries pursue unconventional monetary policies.
As lacklustre economic conditions persist around the world, large-scale, high-impact strategies such as zero interest rates and negative interest rates are being carefully considered by central banks across the world. They are likely to become increasingly mainstream and it’s important for investors to understand what their effects may be.
This is the final instalment in a three-part series exploring the effect of unconventional monetary policies on economies and financial markets. In the previous piece we looked at Japan and Germany’s approach to unconventional monetary policies. In this story, we’ll look at the impact they have had on different asset classes, with a special focus on sovereign bonds.
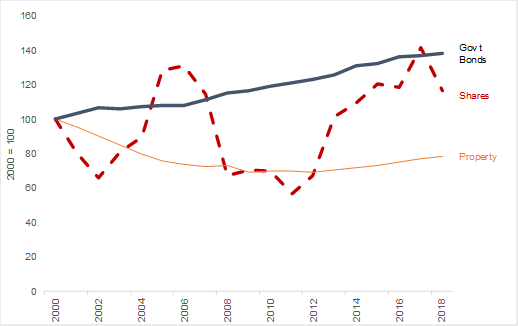
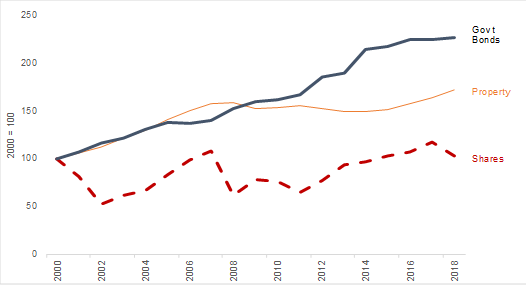
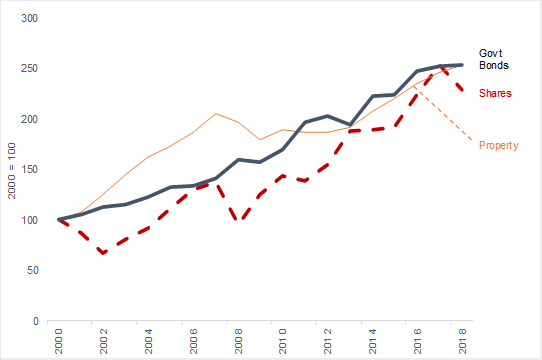
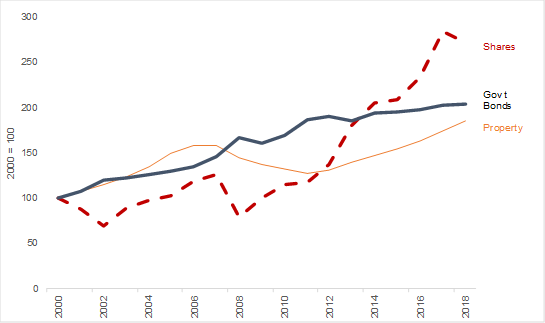
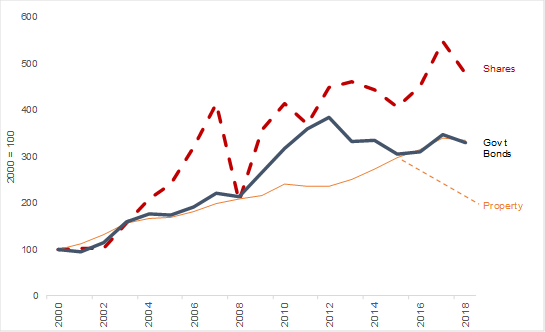
Figure 1: A comparison of performance over time across Japan, the UK, the Eurozone and the US for local shares, residential property and government bonds.
Japan
Figures have been based to 100 starting in the year 2000. Source: JCB team analysis based on data from Bloomberg and the OECD.
Eurozone
Figures have been based to 100 starting in the year 2000. Source: JCB team analysis based on data from Bloomberg and the OECD.
United Kingdom
Figures have been based to 100 starting in the year 2000. Source: JCB team analysis based on data from Bloomberg and the OECD.
United States of America
Figures have been based to 100 starting in the year 2000. Source: JCB team analysis based on data from Bloomberg and the OECD.
Australia (for reference)
Figures have been based to 100 starting in the year 2000. Source: JCB team analysis based on data from Bloomberg and the OECD.
Notes: Shares – TOPIX, FTSE All Shares TR, Eurostoxx 50 TR, S&P 500 TR, S&P/ASX300 TR, Property – OECD house price data, Govt Bonds – relevant local treasury bond indices. All income, dividends and coupons are assumed to have been re-invested into the relevant index. Past performance is not an indicator of future performance.
Investors have been forced to take on more risk in pursuit of returns or yield as central banks have lowered interest rates to near zero, zero or less. As such, investors have had to move up the risk spectrum to generate returns, while being penalised for holding onto cash given the low interest rate environment.
This has encouraged investors to allocate funds to more speculative assets such as emerging market debt, leveraged loans and private equity. But, while these instruments offer attractive yields, they also carry material, and often hidden, risks. With return expectations falling given myriad nearer-term economic headwinds, risk has been cheapened by these policies and risen in investor portfolios. These are typical features of a late-cycle environment.
At the same time, central bank rhetoric has altered investor beliefs. When poor economic data is released, central banks have further eased monetary policy, a strategy that has become increasingly ineffective. More and more accommodation is required just to maintain economic growth.
Risky assets rally hard in this environment. But markets have been lulled into a false sense of security. This has the potential to wrong-foot investors, especially in times of crisis.
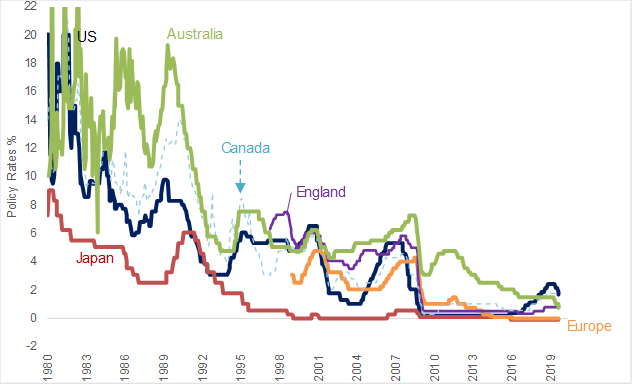
Figure 2: The secular decline in policy rates around the world. Since the GFC, these conditions have aided asset class returns.
Source: JCB team analysis based on data from Bloomberg. Past performance is not an indicator of current or future performance.
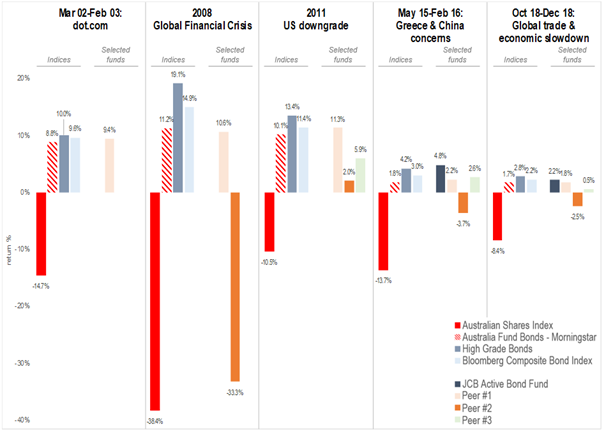
Figure 3: How high grade sovereign bonds perform in times of market stress.
High grade bonds have historically defended and protected when needed.
Source: JCB team analysis based on data from Bloomberg & Morningstar. Past performance is not an indicator of current or future performance.
Where to from here?
The world continues deeper into a late-cycle phase, one in which investors are encouraged by policy makers to reach for yield and return in an increasingly uncertain time. Thoughtful portfolio construction is one of the keys to navigating these difficulties.
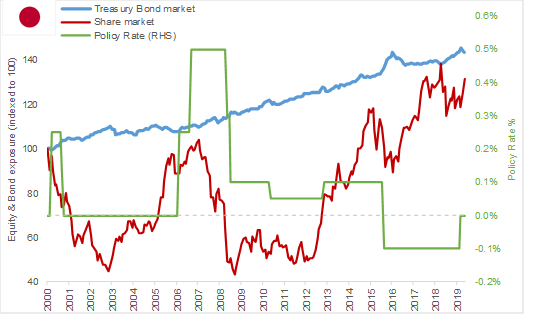
As the Japanese experience demonstrates, traditional asset classes such as cash endure difficult outcomes under these conditions. Bonds are the exception. They can offer compounding qualities that prove invaluable in a low-return environment.
Investors who have tilted their portfolios towards risky assets such as shares and property have been conditioned since the GFC to believe returns are virtuous and markets are supported by central banks doing ‘whatever it takes’ to maintain an even economic keel. This is understandable when considering the strong performance shares and property have enjoyed in recent years. But this environment is unlikely to persist.
Against this backdrop, high-grade sovereign bonds have an enduring and a nearer-term role to play. While forward return expectations for all asset classes are somewhat dampened relative to historic trends, high-grade sovereign bonds offer benefits such as diversification.
High-grade bonds grind out returns and dampen risky asset exposures, even in a muted yield environment. They also deliver compound income over time and provide constructive returns. And, while their returns are likely to be moderated relative to trend, high-grade sovereign bonds offer protection against cyclical downturns and risky assets.
They also enjoy other advantages such as being backed by highly-rated governments including Australia which, alongside Canada and Switzerland, is one of three AAA-rated countries with widescale, functioning bond markets. As stable and well-regulated nations, investors are confident governments can make good on their ongoing debt obligations, which supports the sovereign bond market.
Given the uncertainty and rising pressures in financial markets, proven sources of defensiveness and diversification such as sovereign bonds should help investors mitigate inevitable market pitfalls. In fact, there’s a case for having both domestic and global high-grade sovereign bond exposures in portfolios.
Figure 4: The Japanese investment landscape over time – sovereign bonds delivered compounding returns.
Source: JCB team analysis based on data from Bloomberg.
Central banks are likely to continue to use unconventional monetary policies in a persistent low-rate environment. As a result, it’s worthwhile for investors to consider the role of sovereign bonds in their portfolio to help mitigate risk and generate returns.
Subscribe for more insights like this or call 1800 940 599.
This information is provided by JamiesonCooteBonds Pty Ltd ACN 165 890 282 AFSL 459018 (‘JCB’). This information has been prepared for the purposes of providing general information and should not be considered advice or a recommendation to investors or potential investors in relation to holding, purchasing or selling units and/or investments and does not take into account your particular investment objectives, financial situation or needs. Past performance is not a reliable indicator of future performance. All investments contain risk. Before acting on any information you should consider the appropriateness of the information having regard to these matters, any relevant offer document and in particular, you should seek independent financial advice.
This information is for professional and wholesale investors only and has been prepared by JamiesonCooteBonds Pty Ltd ACN 165 890 282 AFSL 459018 (‘JCB’). Channel Investment Management Limited ACN 163 234 240 AFSL 439007 (‘CIML’) is the Responsible Entity and issuer of units for the CC JCB Active Bond Fund ARSN 610 435 302, CC JCB Global Bond Fund ARSN 631 235 553 and the CC JCB Dynamic Alpha Fund ARSN 637 628 918 (collectively ‘the Funds’). Channel Capital Pty Ltd ACN 162 591 568 AR No. 001274413 (‘Channel’) provides investment infrastructure and distribution services for JCB and is the holding company of CIML.
This information is supplied on the following conditions which are expressly accepted and agreed to by each interested party (‘Recipient’). This information contains general financial product advice only and has been prepared without taking into account the objectives, financial situation or needs of any particular person. It is intended solely for wholesale clients (including sophisticated investors) as defined under sections 761G and 761GA of the Corporations Act 2001 (Cth). JCB is not licensed in Australia to provide financial product advice or other financial services to retail investors.
The information provided should not be considered personal advice, a recommendation, or an offer to invest in the Funds. Recipients should not rely on this information in making investment decisions. A Recipient should, before making any investment decisions, consider the appropriateness of the information, and seek professional advice.
Neither JCB, Channel, CIML or their representatives and respective employees or officers (collectively, ‘the Beneficiaries’) make any representation or warranty, express or implied, as to accuracy, reliability or completeness of this information or subsequently provided to the Recipient or its advisers by any of the Beneficiaries, including, without limitation, any historical financial information, the estimates and projections and any other financial information derived there from, and nothing contained in this information is, or shall be relied upon, as a promise or representation, whether as to the past or the future. All investments contain risk. Past performance is not a reliable indicator of future performance.
For further information and before investing, please read the Product Disclosure Statement and Target Market Determination which is available from www.channelcapital.com.au
Thank you for sharing your feedback.
Oops! Something went wrong while submitting the form.
Perspective, not prediction.
Timely views from the investment team on policy, market structure and portfolio construction.