The information, products and services described on this website are intended solely for persons in Australia who are wholesale clients within the meaning of section 761G of the Corporations Act 2001 (Cth)). They are not directed at, and should not be relied upon by, retail clients.
By clicking Confirm below, you confirm that:
You are a wholesale client for the purposes of section 761G of the Corporations Act 2001 (Cth); and
The transitory debate – where will inflation settle by mid-2022?
Kate Samranvedhya, Deputy Chief Investment Officer
The current question amongst market commentators is who’s winning the transitory vs secular inflation debate?
The most recent (August 2021) U.S. CPI data disappointed the inflation bulls, with headline CPI coming in at 0.3% month-on-month versus the market expectation of 0.4%. The more refined core CPI was only 0.1% month-on-month versus 0.3% consensus. Considering the past two months, the transitory inflation camp has been gaining momentum, as we anticipated, with outsized items such as used cars prices normalising in their trajectory.
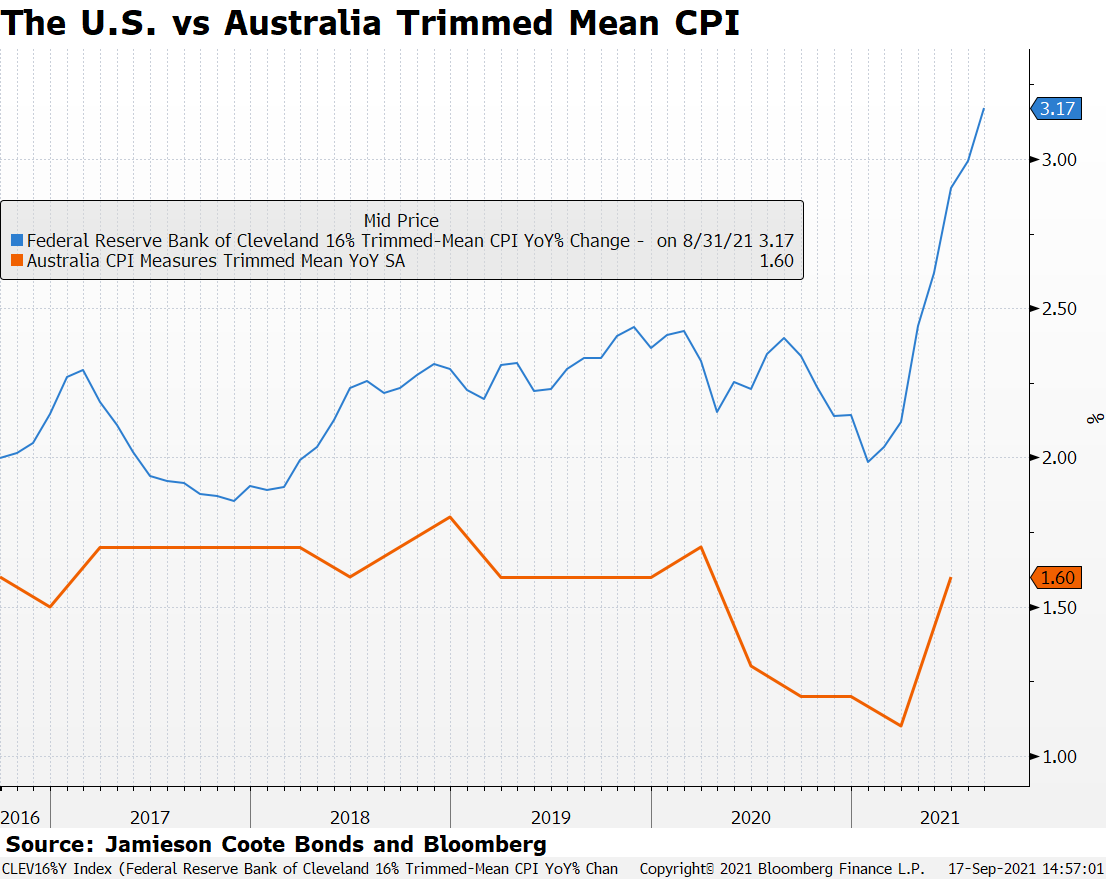
On the other hand, there are signs specific to the U.S. that price pressure can be stickier than the pre-COVID era. One is the trimmed mean measure of inflation, which removes the items with the largest price increases and decreases or by taking the middle range of CPI components.
The U.S. trimmed mean inflation (indicated by the blue line) has been in a stable range of just under 2% (up to 2.5% after the GFC) leading up to COVID-19. Notably, it has broken this benign pattern and trended upwards in the absence of an obvious base effect. On the other hand, we sense that Australia’s trimmed mean inflation surge will likely peter out when the weak initial data (or base effect) falls from the rolling metrics by Q3/2021.
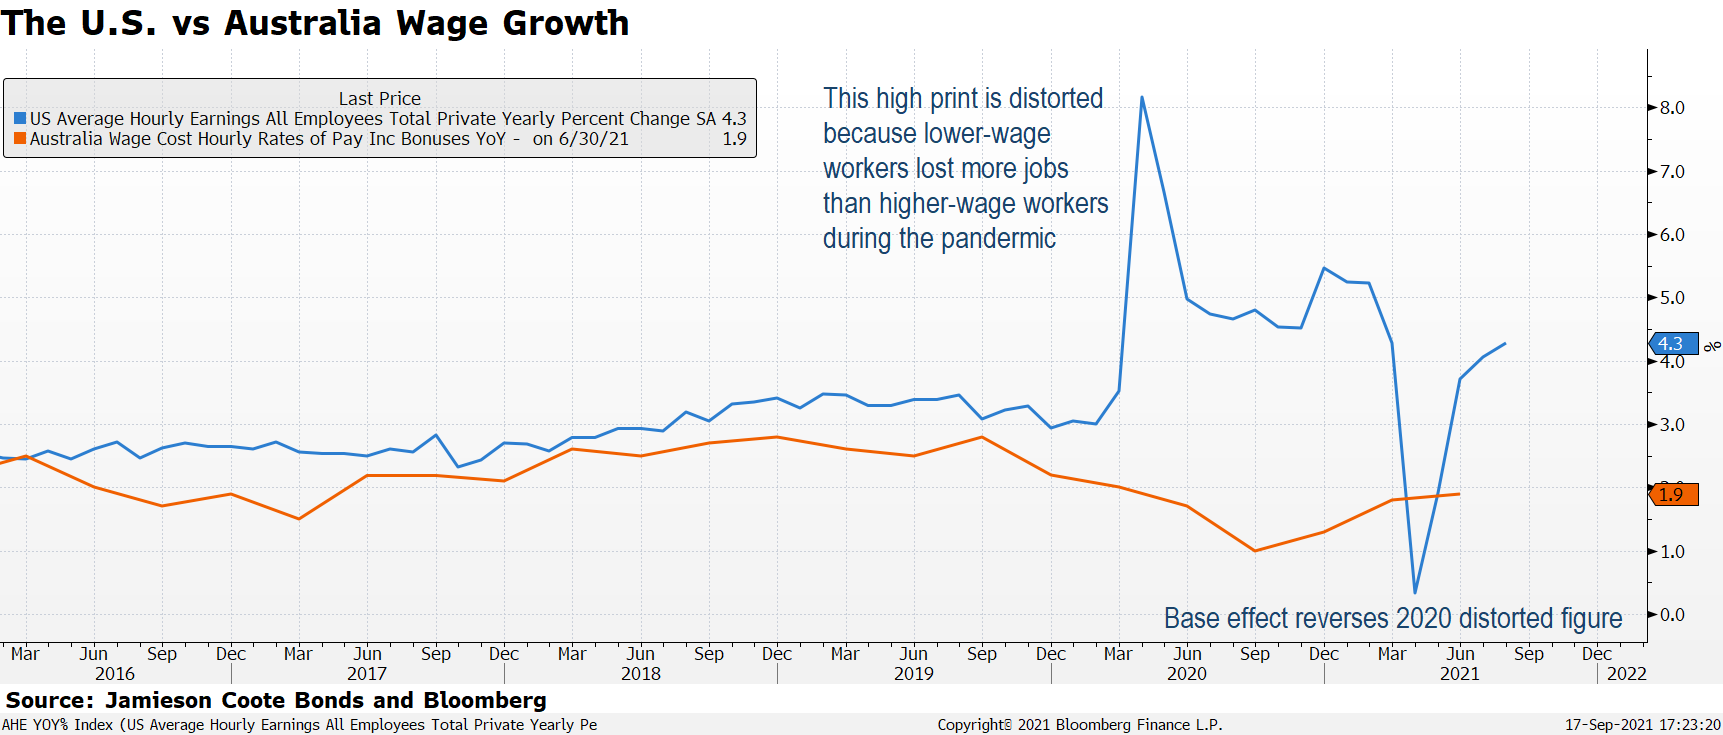
The other interesting sign, specific to the U.S., is prevailing wage pressures. The graph below displays the U.S. wage growth (indicated by the blue line), which shows upward wage pressures relative to the pre-COVID era. Anecdotally, this may reflect a few things. Firstly, the most obvious is that the minimum wage in the U.S. has been raised to $15. Secondly, there is a sense that lower-wage workers have developed new skills during the lockdown and have moved on to higher-paying jobs. Thirdly, people have adapted to working-from-home and prefer more autonomy or more flexible working arrangements. If employers want workers in the office as was once the norm, they often have to pay higher wages to get the workers back in the office.
Once again, the picture is very different in Australia (depicted by the orange line), where wage growth is still sub 2% and wage pressure seems far off (apart from specific sectors like scientific and professional services). The August 2021 job report shows a dip in jobs, almost back to pre-COVID levels and a further dip in number of hours worked.
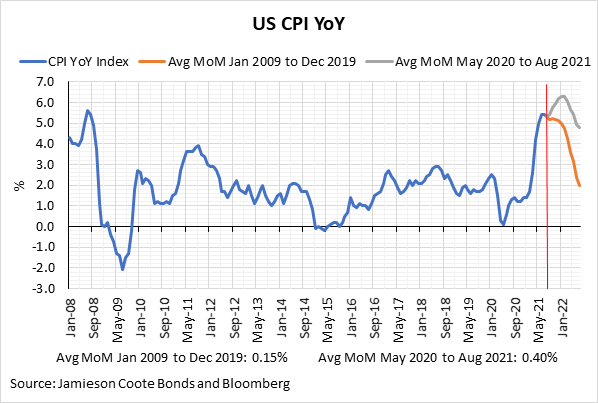
The crux of the transitory debate, however, lies in where inflation will really settle by the middle of 2022. The year-on-year U.S. inflation number, which everyone often refers to, will likely remain elevated either sideways or slightly higher into the end of 2021, as re-opening effects continue to wash through, combined with difficult-to-resolve global supply chain issues. Thereafter, inflation is likely to fall until the middle of 2022.
Hence, the real debate is whether the inflationary pressure will return to the post-GFC, pre-COVID era of just under 2% average year-on-year inflation. Under this narrative, the U.S. Federal Reserve (the Fed) will stay very patient and choose to move slowly in both the timing and the pace of its interest rate hikes. The tapering announcement has already been headlined for so long that the market has been well conditioned. This move will likely coincide with a reduction in U.S. Treasury bond supply that may fortunately not have the same tantrum effect on the bond market as in 2013.
Conversely, there is still some risk that inflation settles at a slightly higher range than historical trends. A 2-3% year-on-year range would look like this and hark back to the period in the 1990’s leading up to the GFC. In the present moment, supply chain problems stemming from the Delta variant still feeds into this theme. The Fed may overlook the supply shock in the beginning, as long as it does not shift inflation expectations permanently.
This information is for professional and wholesale investors only and has been prepared by JamiesonCooteBonds Pty Ltd ACN 165 890 282 AFSL 459018 (‘JCB’). Channel Investment Management Limited ACN 163 234 240 AFSL 439007 (‘CIML’) is the Responsible Entity and issuer of units for the CC JCB Active Bond Fund ARSN 610 435 302, CC JCB Global Bond Fund ARSN 631 235 553 and the CC JCB Dynamic Alpha Fund ARSN 637 628 918 (collectively ‘the Funds’). Channel Capital Pty Ltd ACN 162 591 568 AR No. 001274413 (‘Channel’) provides investment infrastructure and distribution services for JCB and is the holding company of CIML.
This information is supplied on the following conditions which are expressly accepted and agreed to by each interested party (‘Recipient’). This information contains general financial product advice only and has been prepared without taking into account the objectives, financial situation or needs of any particular person. It is intended solely for wholesale clients (including sophisticated investors) as defined under sections 761G and 761GA of the Corporations Act 2001 (Cth). JCB is not licensed in Australia to provide financial product advice or other financial services to retail investors.
The information provided should not be considered personal advice, a recommendation, or an offer to invest in the Funds. Recipients should not rely on this information in making investment decisions. A Recipient should, before making any investment decisions, consider the appropriateness of the information, and seek professional advice.
Neither JCB, Channel, CIML or their representatives and respective employees or officers (collectively, ‘the Beneficiaries’) make any representation or warranty, express or implied, as to accuracy, reliability or completeness of this information or subsequently provided to the Recipient or its advisers by any of the Beneficiaries, including, without limitation, any historical financial information, the estimates and projections and any other financial information derived there from, and nothing contained in this information is, or shall be relied upon, as a promise or representation, whether as to the past or the future. All investments contain risk. Past performance is not a reliable indicator of future performance.
For further information and before investing, please read the Product Disclosure Statement and Target Market Determination which is available from www.channelcapital.com.au
Thank you for sharing your feedback.
Oops! Something went wrong while submitting the form.
Perspective, not prediction.
Timely views from the investment team on policy, market structure and portfolio construction.