The information, products and services described on this website are intended solely for persons in Australia who are wholesale clients within the meaning of section 761G of the Corporations Act 2001 (Cth)). They are not directed at, and should not be relied upon by, retail clients.
By clicking Confirm below, you confirm that:
You are a wholesale client for the purposes of section 761G of the Corporations Act 2001 (Cth); and
Why no inflation pass-through is a bigger concern for China
Producers in both China and the US are facing higher costs, prompting growing concerns that inflation could threaten the global economy – but China isn’t waiting to find out given its recent history with inflation.
Interestingly, Chinese consumers are facing much less pricing pressure than their American peers, so why are the Chinese more concerned over higher commodity prices? This could be a potential headwind to Chinese economic growth. Top Chinese officials like Premier Li Keqiang and Vice Premier Liu He recently expressed concerns for manufacturers and the adverse effect of rising commodity prices including the potential pass-through to consumers for some goods. In response, Chinese regulators were tasked with curbing the excessive speculation in the commodity market by imposing new limits on the trading of commodities and increasing some export taxes.
China has clear reasons to fear inflation with memory of past price increases still vivid, including the +135.2% surge of pork prices and +5.2% consumption inflation in February 2020. But, in our view, the threat of no inflation pass-through is more pressing.
Is China exporting higher prices?
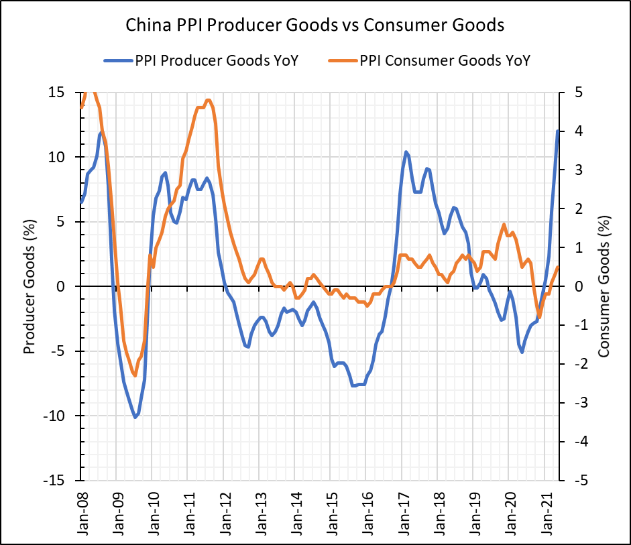
Since joining the World Trade Organisation in 2001, China has engineered a complete industrial system. The upstream raw materials sectors have been dominated by big companies, which are closely associated with central or local governments. These companies have the pricing power to transfer the input cost pressure to mid- and downstream companies. Notably, the producer goods price increased by +12.0% in the last twelve months, as of May 2021. But the inflation pass-through stopped here and did not flow downstream. The price of consumer goods increased by only +0.5% during the same period. Mid- and downstream companies failed to pass the higher input cost to the consumers. A few factors contributed to the no pass-through of inflation which are discussed below.
Figure 1 – China Producer Goods vs Consumer Goods
Source: Bloomberg, JCB
Firstly, the competition at the mid- and downstream level is fierce. When Chinese manufacturers had a limited technology edge, they won market share via lower prices thanks to cheap labor costs. This led to overcapacity and triggered the supply side structural reforms of 2015. Prior to the full blown COVID-19 impacts, industrial upgrading and technology innovation was still undergoing and far from complete. In short, if your competitive edge is price, you cannot jack-up price so easily.
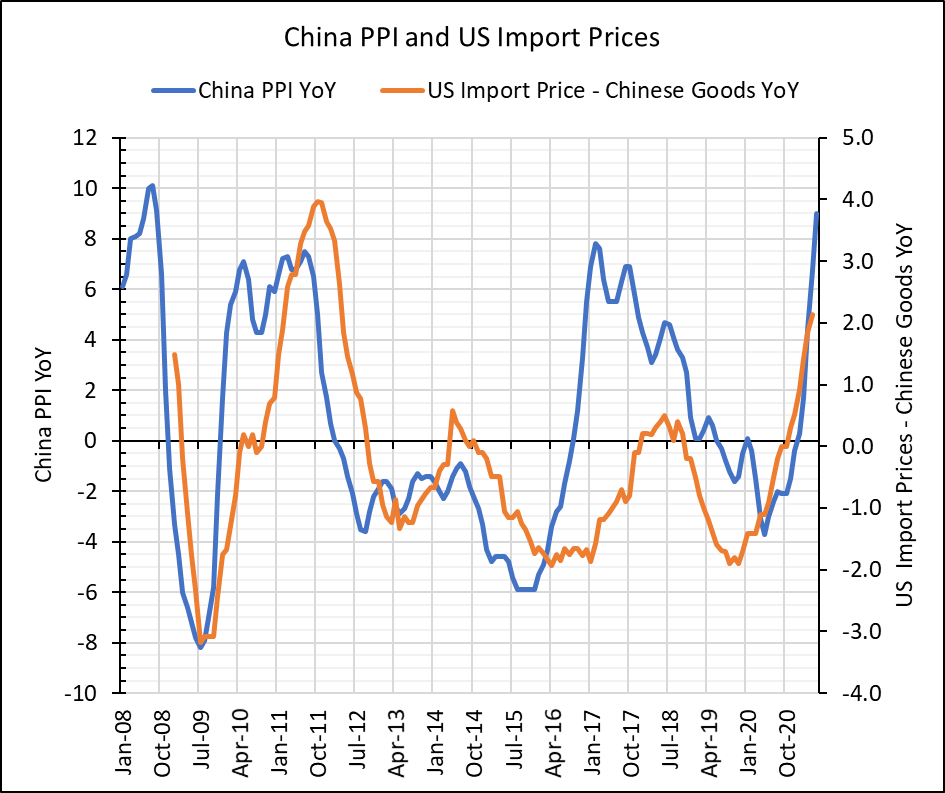
Secondly, there is no positive domestic demand shock in China. Unlike many developed countries, the Chinese government didn’t implement a large fiscal transfer to boost household balance sheets. The recent retail sales and service output data showed that demand is growing but at a lower-than pre-COVID-19 speed. With largely stable domestic demand, mid- and downstream manufacturers could not raise prices without losing market share. Due to the strong recovery of overseas demand, those downstream manufacturers, who have the capability to compete in overseas markets, may charge higher prices, i.e. exporting the inflation. However, the recent appreciation of RMB has posed a headwind. The latest survey data shows the slowdown of new export orders.
Figure 2 – Chinese producers pass through the price pressure to US customers
Source: Bloomberg, JCB
Overall, high commodity prices without inflation pass-through simply means profit squeezing for mid- and downstream firms.
In late May 2021, Chinese state media reported that some downstream producers stopped taking new orders as the more they produced the more they lost. In our view, China shouldn’t worry too much about the threat of the high consumer inflation for now as it is difficult for downstream producers to pass through the price pressure. However, the profit squeezing caused by the no pass-through is right here. We believe it is a headwind to Chinese economic growth, which explains why policy makers are tackling the high commodity prices.
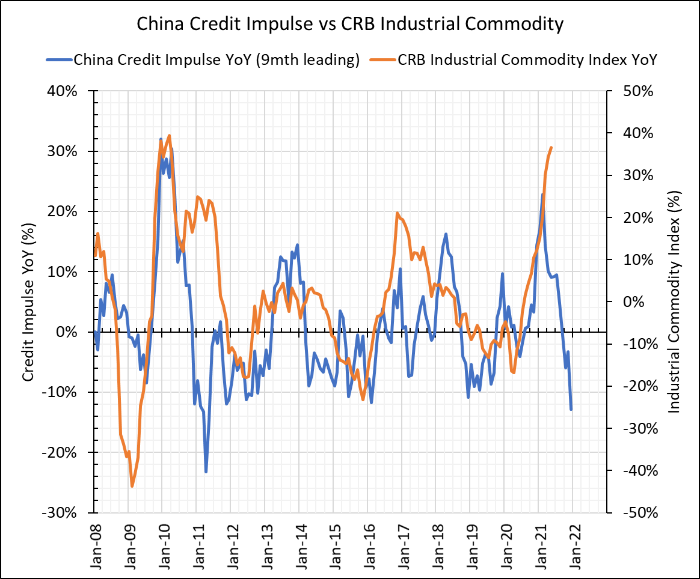
Some Chinese trading firms have increased inventory of physical commodities and tried to corner the market. Regulators called them to stop the market speculation and manipulation. China would also maintain the macro prudent policy and keep the credit impulse low. This would avoid spurring the property bubble further. Historically, lower China credit impulse was linked to lower commodity prices.
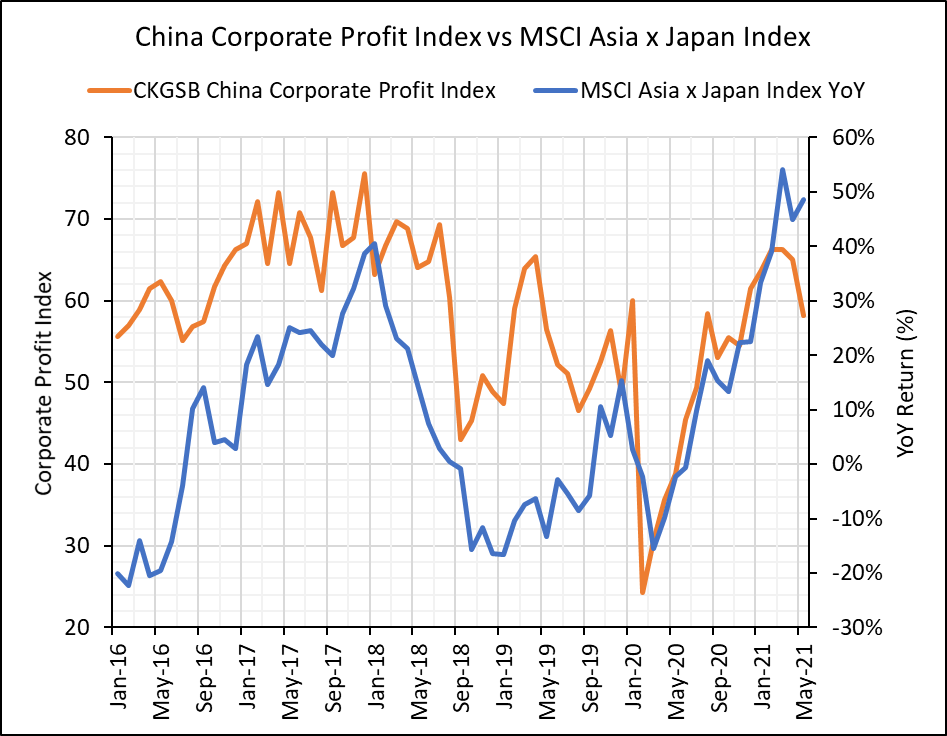
However, things may be different this time. The expansionary fiscal policy from the Biden Administration could make the U.S., instead of China, the marginal buyer in the commodity market. While U.S. consumers use the stimulus money to pay for higher gasoline prices during their summer trips, Chinese producers could face further profit squeezing. History suggests that the turning of profitability in the Chinese corporate sector can have significant impacts on regional equity markets, with associated impacts across the macro spectrum, investors should pay attention to the lack of pass-through pricing power given this higher inflation impulse in China as an early warning sign of fading corporate profitability.
Figure 3 – China Credit Impulse falling
Source: Bloomberg, JCB
Figure 4 – China Corporate Profit Index vs MSCI Asia x Japan Index
This information is for professional and wholesale investors only and has been prepared by JamiesonCooteBonds Pty Ltd ACN 165 890 282 AFSL 459018 (‘JCB’). Channel Investment Management Limited ACN 163 234 240 AFSL 439007 (‘CIML’) is the Responsible Entity and issuer of units for the CC JCB Active Bond Fund ARSN 610 435 302, CC JCB Global Bond Fund ARSN 631 235 553 and the CC JCB Dynamic Alpha Fund ARSN 637 628 918 (collectively ‘the Funds’). Channel Capital Pty Ltd ACN 162 591 568 AR No. 001274413 (‘Channel’) provides investment infrastructure and distribution services for JCB and is the holding company of CIML.
This information is supplied on the following conditions which are expressly accepted and agreed to by each interested party (‘Recipient’). This information contains general financial product advice only and has been prepared without taking into account the objectives, financial situation or needs of any particular person. It is intended solely for wholesale clients (including sophisticated investors) as defined under sections 761G and 761GA of the Corporations Act 2001 (Cth). JCB is not licensed in Australia to provide financial product advice or other financial services to retail investors.
The information provided should not be considered personal advice, a recommendation, or an offer to invest in the Funds. Recipients should not rely on this information in making investment decisions. A Recipient should, before making any investment decisions, consider the appropriateness of the information, and seek professional advice.
Neither JCB, Channel, CIML or their representatives and respective employees or officers (collectively, ‘the Beneficiaries’) make any representation or warranty, express or implied, as to accuracy, reliability or completeness of this information or subsequently provided to the Recipient or its advisers by any of the Beneficiaries, including, without limitation, any historical financial information, the estimates and projections and any other financial information derived there from, and nothing contained in this information is, or shall be relied upon, as a promise or representation, whether as to the past or the future. All investments contain risk. Past performance is not a reliable indicator of future performance.
For further information and before investing, please read the Product Disclosure Statement and Target Market Determination which is available from www.channelcapital.com.au
Thank you for sharing your feedback.
Oops! Something went wrong while submitting the form.
Perspective, not prediction.
Timely views from the investment team on policy, market structure and portfolio construction.