The information, products and services described on this website are intended solely for persons in Australia who are wholesale clients within the meaning of section 761G of the Corporations Act 2001 (Cth)). They are not directed at, and should not be relied upon by, retail clients.
By clicking Confirm below, you confirm that:
You are a wholesale client for the purposes of section 761G of the Corporations Act 2001 (Cth); and
Risk markets appear to be battening down the hatches as winter is coming in the Northern Hemisphere and the beneficiaries of the phenomenal global fiscal and monetary injections in the first quarter of the year will have to navigate through some seasonally challenging periods into year end.
These seasonal headwinds are exacerbated by the pandemic concerns as the summer winds down with reports last week out of the UK from its Chief Scientific Officer that they could experience 50,000 new virus cases a day by mid-October without further action. Equities historically underperform at this stage of the year, particularly in election years, and given the eye-watering valuations, it’s not surprising that they have retraced sharply as the spectre of further draconian shutdowns, politicians at loggerheads over fiscal stimulus and cashflow concerns pervade.
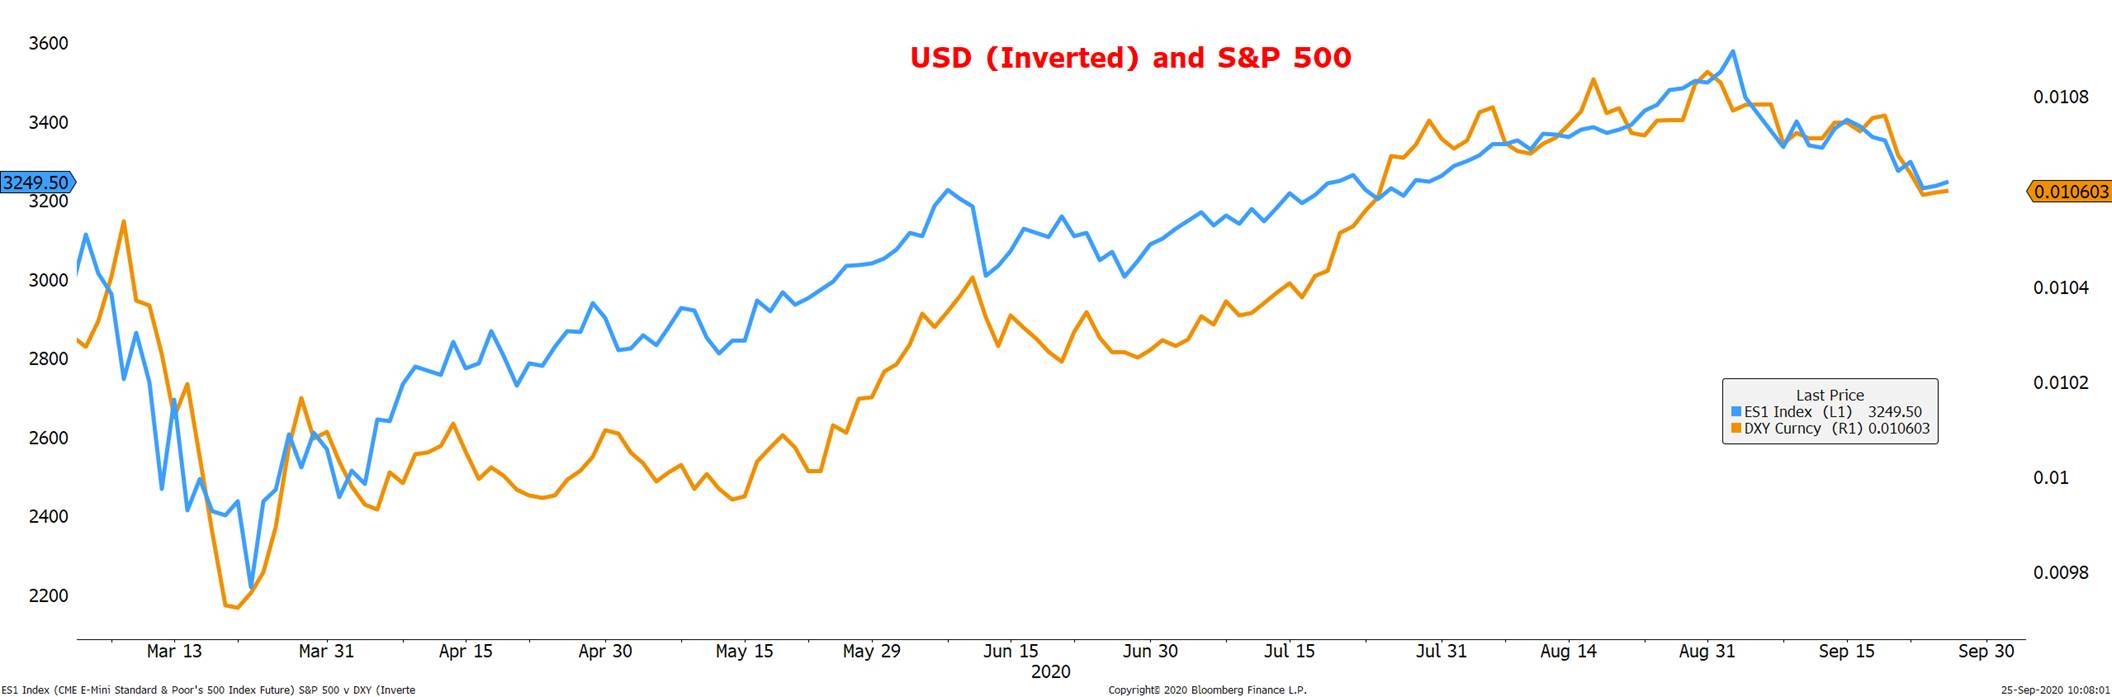
All of this year’s asset performers are starting to show some vulnerabilities and we believe the path of the US Dollar will play a major role heading into year end, and strength there will make it difficult for other asset classes. The death of the King Dollar appears premature and the inverse relationship between the weaker greenback and US equities has been steadfast since March as the chart below demonstrates, with the negative 30-day correlation between the US dollar and the S&P 500 increasing, running at around -0.26.
The US dollar has showed signs of basing since 1 September, which has also coincided with a 12% fall in the Nasdaq, and a 21% drop in Apple from its high on 1 September, and leaves room for further medium term mean reversion into year end.
Relationship between the US dollar and US equities
Source: Bloomberg
It’s unsurprising that many asset classes that have gorged on low rates afforded to them by global bond markets are having some indigestion with many uncertainties still to play out into year-end; the US election, Brexit, and a discovery/implementation of a Covid-19 vaccine.
How do we get the economy back on track?
Risk markets still replicate an orchid – they need almost perfect conditions to thrive, and they have started to wilt with monetary and fiscal expansion stalling. Republican and Democrats are trillions apart and with less than 40 days until the election, their focus on securing votes is taking their attention away from the task of putting the economy back on track, as we have witnessed with nominations to fill the supreme court seat vacated by Ruth Bader Ginsberg. The need for fiscal stimulus was recently underscored by Chair of the US Federal Reserve (the Fed) Jerome Powell whose monetary toolkit is starting to look barren, "There is downside risk probably coming if some form of that support doesn't continue," the Fed chairman pleaded to politicians last week.
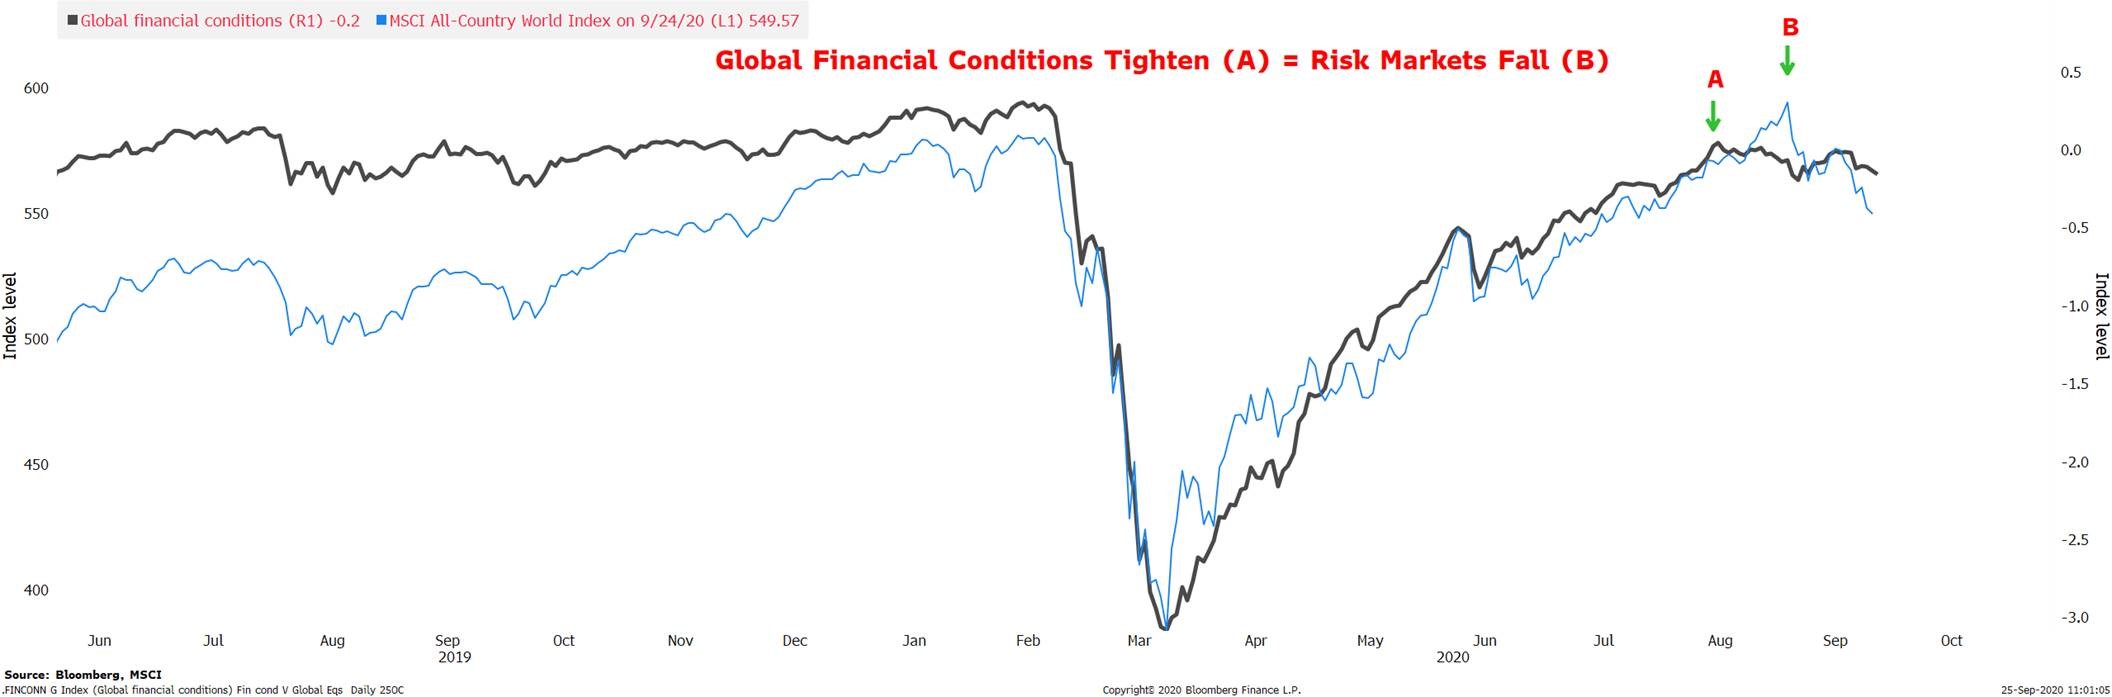
The recent correction is a salient reminder of the herd investing mentality and lack of investment alternatives as the equity, foreign exchange, commodity and inflation markets all moved in lockstep despite the benign range in bond markets. The subtle tightening of global financial conditions in August, as we can see from the below chart, was a trigger for the correction and underscores the abusive relationship liquidity has fostered with asset classes, and will make it very difficult for higher bond yields in the foreseeable future.
Source: Bloomberg, MSCI
The aggressive financial stimulus provided earlier in the year from authorities has given a temporary rise to economic data and asset classes and that can be expected to subside as we have already started to see in various commodity markets, as the stockpiling effect and speculative buying appears to have run its course.
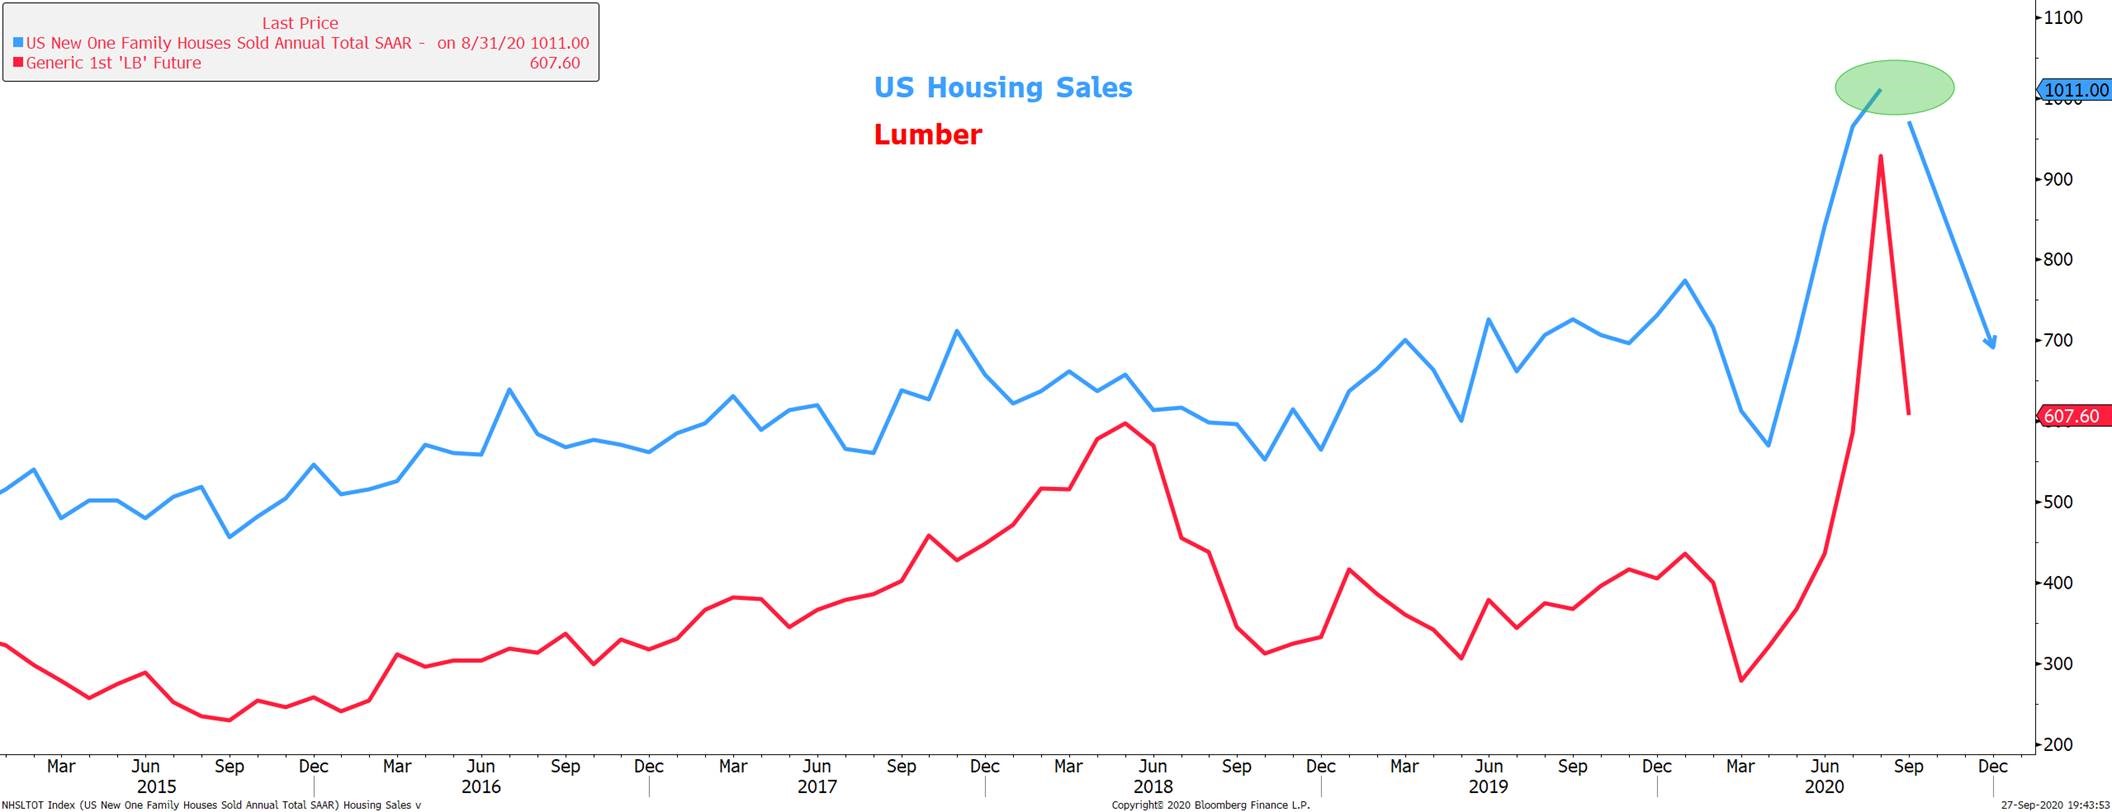
The poster child in the commodity market rally has been the parabolic move higher in the lumber market and that has corrected sharply lower of late, which sends a warning signal to the heartbeat of the US economy - the housing market, given the historically tight relationship. This highlights the risks and vulnerabilities of markets and economies going forward as the effects of the liquidity and stimulus injections start to wear off and we would anticipate further economic growth and earnings downgrades into year end.
Source: Bloomberg
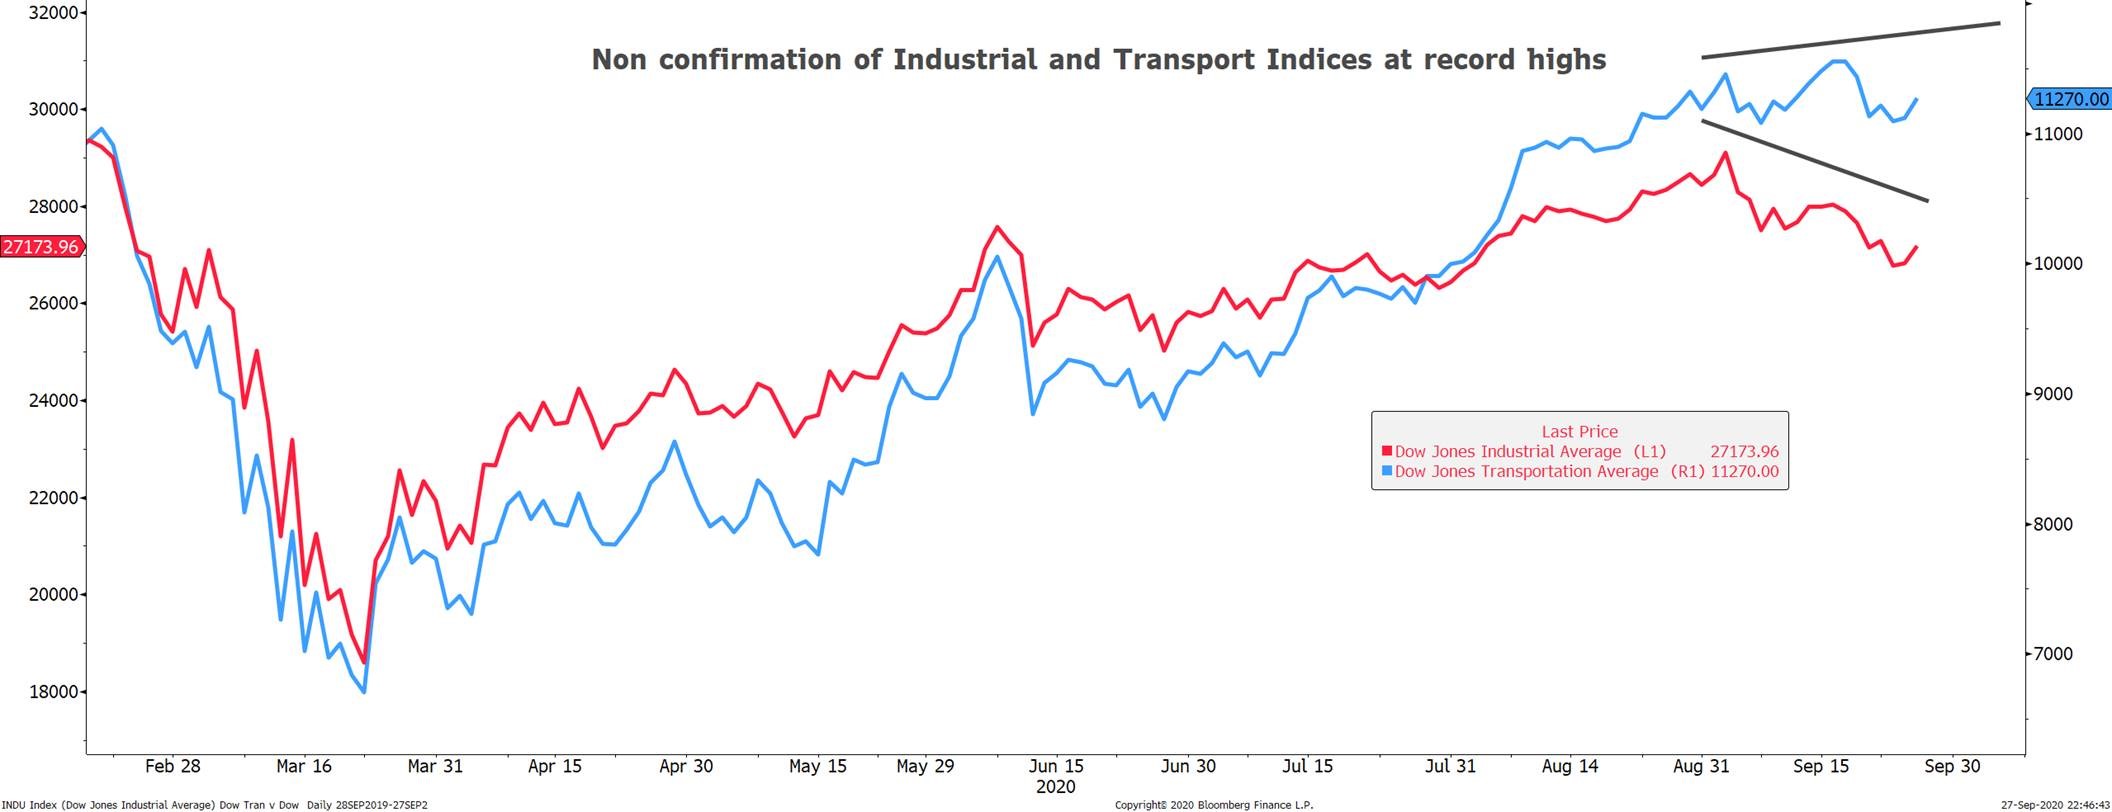
We religiously monitor the price action of global markets and were recently alerted to the warning signs provided by the lack of confirmation or conviction demonstrated by equity market price behaviour at their record highs, which corroborates the thesis that risk markets will encounter headwinds into year end. One of the central tenets of Dow Theory − a stream of technical analysis − is that averages or indices must confirm each other, particularly when looking at the equity markets. The recent failure of the Industrials to confirm the Transports higher record high, tarnishes the efficacy of the move and increases the probabilities that an equity correction lower will unfold.
Source: Bloomberg
Looking forward, we believe that the probabilities for risk markets to maintain their upward trajectory into year-end will be challenged, particularly as the US election approaches and the narrative around a harsh winter second wave gathers momentum in the Northern Hemisphere. The sanguine bond market should offer a harbor for investors to protect their portfolios as Central Banks remain in expansionary mode and the economic effects of expiring fiscal support start to bite.
This information is for professional and wholesale investors only and has been prepared by JamiesonCooteBonds Pty Ltd ACN 165 890 282 AFSL 459018 (‘JCB’). Channel Investment Management Limited ACN 163 234 240 AFSL 439007 (‘CIML’) is the Responsible Entity and issuer of units for the CC JCB Active Bond Fund ARSN 610 435 302, CC JCB Global Bond Fund ARSN 631 235 553 and the CC JCB Dynamic Alpha Fund ARSN 637 628 918 (collectively ‘the Funds’). Channel Capital Pty Ltd ACN 162 591 568 AR No. 001274413 (‘Channel’) provides investment infrastructure and distribution services for JCB and is the holding company of CIML.
This information is supplied on the following conditions which are expressly accepted and agreed to by each interested party (‘Recipient’). This information contains general financial product advice only and has been prepared without taking into account the objectives, financial situation or needs of any particular person. It is intended solely for wholesale clients (including sophisticated investors) as defined under sections 761G and 761GA of the Corporations Act 2001 (Cth). JCB is not licensed in Australia to provide financial product advice or other financial services to retail investors.
The information provided should not be considered personal advice, a recommendation, or an offer to invest in the Funds. Recipients should not rely on this information in making investment decisions. A Recipient should, before making any investment decisions, consider the appropriateness of the information, and seek professional advice.
Neither JCB, Channel, CIML or their representatives and respective employees or officers (collectively, ‘the Beneficiaries’) make any representation or warranty, express or implied, as to accuracy, reliability or completeness of this information or subsequently provided to the Recipient or its advisers by any of the Beneficiaries, including, without limitation, any historical financial information, the estimates and projections and any other financial information derived there from, and nothing contained in this information is, or shall be relied upon, as a promise or representation, whether as to the past or the future. All investments contain risk. Past performance is not a reliable indicator of future performance.
For further information and before investing, please read the Product Disclosure Statement and Target Market Determination which is available from www.channelcapital.com.au
Thank you for sharing your feedback.
Oops! Something went wrong while submitting the form.
Perspective, not prediction.
Timely views from the investment team on policy, market structure and portfolio construction.