The information, products and services described on this website are intended solely for persons in Australia who are wholesale clients within the meaning of section 761G of the Corporations Act 2001 (Cth)). They are not directed at, and should not be relied upon by, retail clients.
By clicking Confirm below, you confirm that:
You are a wholesale client for the purposes of section 761G of the Corporations Act 2001 (Cth); and
Paul Chin, Executive Director, Chief Executive Officer, Head of Investment Strategy & ESG
Key Takeaways
Uncovering the hidden risks: High-yield credit funds offer attractive returns but come with hidden risks, such as default exposure and liquidity constraints. Not all fixed income assets carry the same level of risk, making due diligence essential.
The rise of private credit: As banks pull back on corporate lending, private credit funds are filling the gap. These funds provide varied opportunities, but investors must scrutinise sector focus, loan terms, and borrower stability to avoid potential pitfalls.
Balancing risk and stability: A well-diversified portfolio that blends high-yield credit with more stable investments, such as government bonds, can provide resilience and mitigate exposure to volatility.
The allure of high yields: what lies beneath
High yield credit funds often appear enticing, promising higher returns compared to traditional fixed income assets. But beneath the surface, they come with hidden complexities that can catch investors off guard. While these funds can generate strong income, risks such as liquidity constraints, market sensitivity, and potential defaults lurk in the background, waiting to surface during periods of economic stress.
Private credit: a double-edged sword
Private credit has become a go-to alternative as banks retreat from corporate lending across the world. But not all private credit opportunities are created equal. Investors must weigh key considerations, including:
Sector focus: Are the loans directed toward stable industries or volatile sectors like property development?
Business maturity: Are the borrowers established firms or distressed companies seeking last-resort financing?
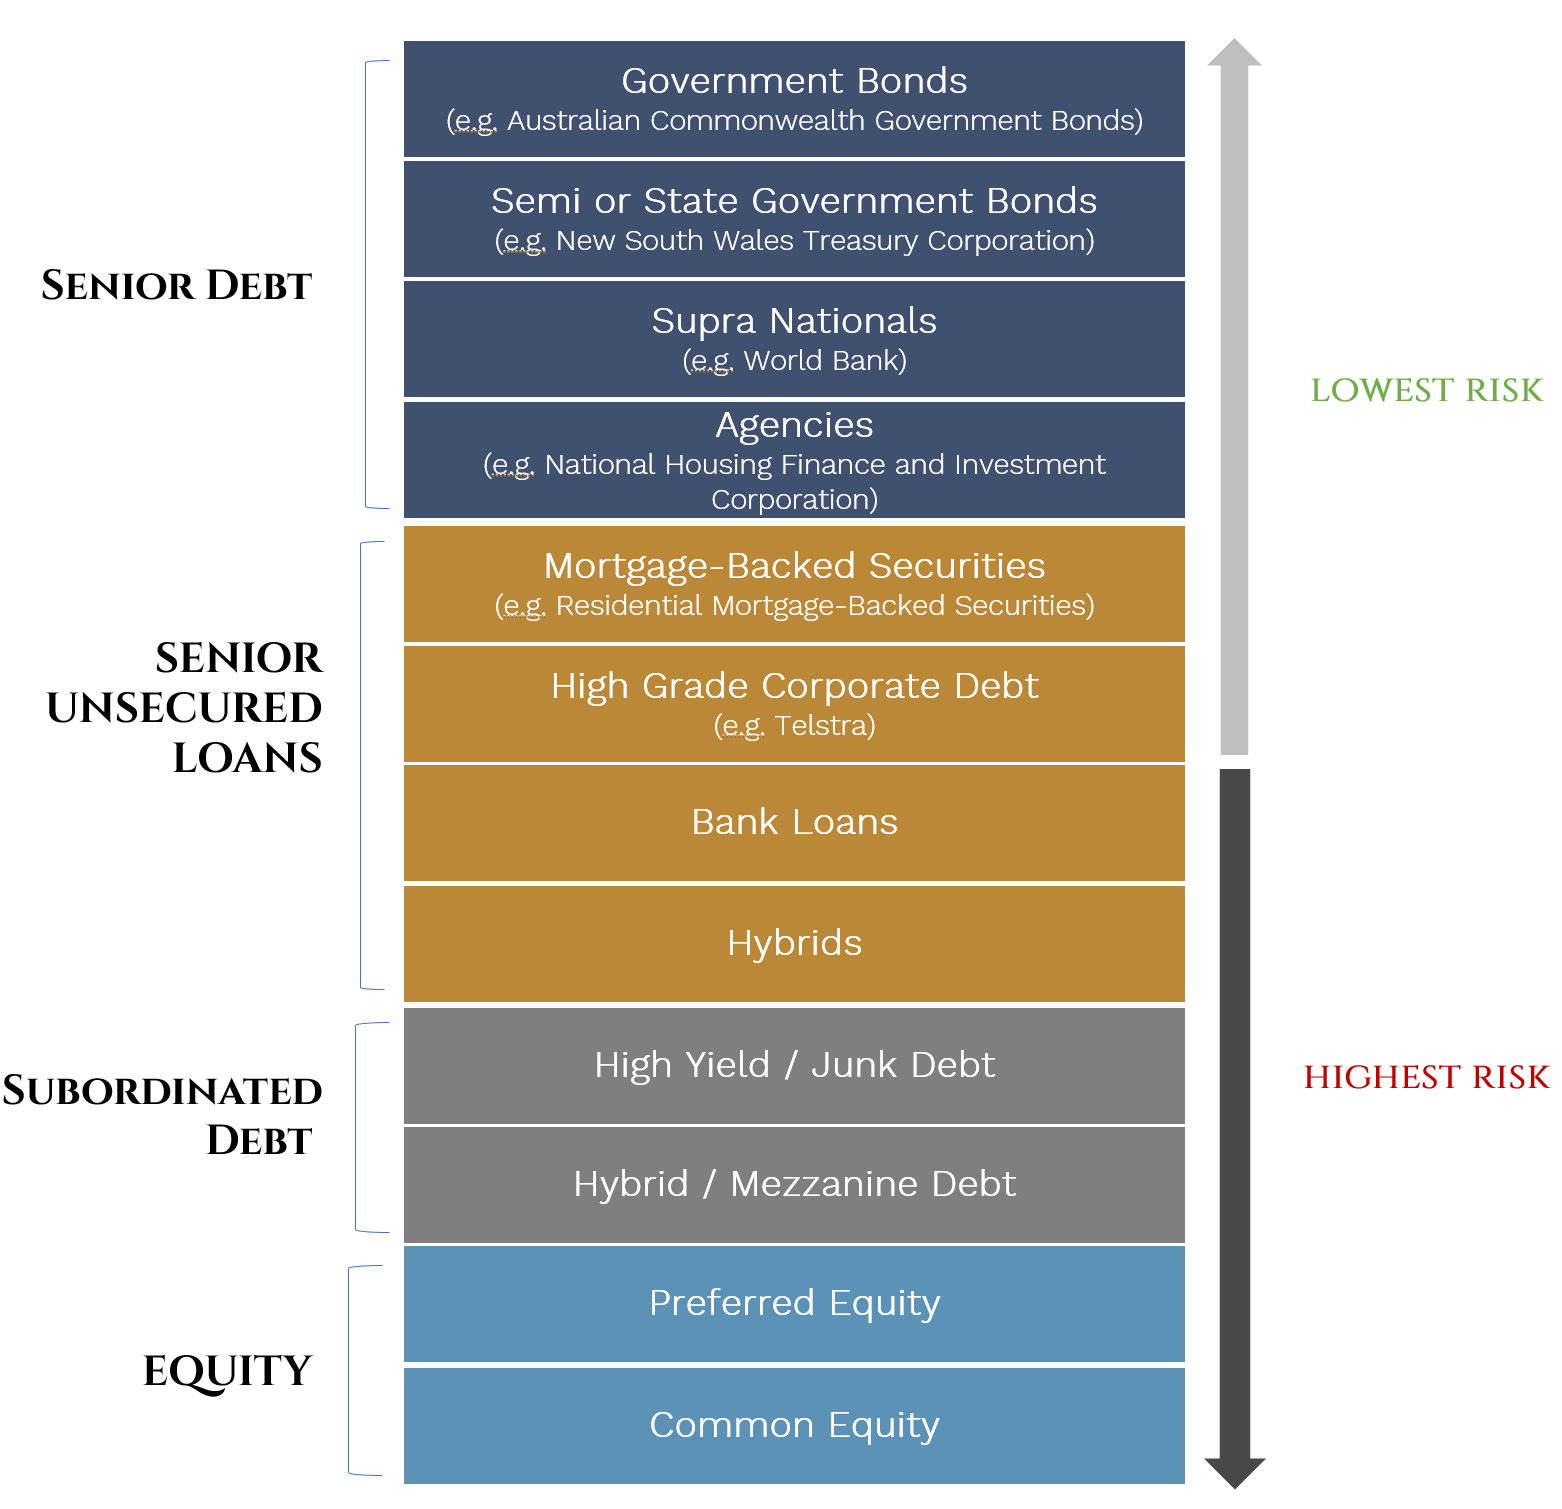
Capital structure positioning: Are loans secured with priority claims or unsecured with greater risk exposure? In other words, what is the order in which a lender gets paid back in the event of a company’s financial difficulties or liquidation.
Loan terms: Are the agreements structured to protect investors, or do they favour flexibility for borrowers?
While private credit offers a pathway to strong returns, failing to assess these variables can lead to unexpected risks that may only become apparent when markets take a turn.
Liquidity: the trap of limited access
One of the most overlooked risks in private markets is liquidity—or the lack of it. Unlike public market investments that can be easily traded, private credit funds often impose long lock-up periods and infrequent redemption windows. When market stress hits, liquidity can dry up quickly, leaving investors trapped.
The market dislocations of March 2020 highlighted that during times of market stress, fixed income funds may raise "sell spreads" to limit investor exits, making it more difficult to liquidate investments at desired prices. This exposed the illusion of liquidity, showing that what may appear to be easily tradable assets can become illiquid during periods of crisis. It serves as a reminder that investors need to carefully assess the true liquidity risks of their investments, particularly in volatile market conditions.
Default risk: the cost of chasing yield
The trade-off for higher returns is greater default risk. When companies face financial strain, meeting debt obligations becomes challenging, leading to potential losses for investors. The volatility of high yield credit means that economic downturns can cause sharp declines in asset values. Just as a seemingly stable structure can collapse under hidden weaknesses, a single borrower default can unravel expected returns, making portfolio risk management essential.
Transparency: seeing beyond the surface
Valuation discrepancies in private credit add another layer of risk. Unlike publicly traded securities, private credit valuations are periodic and can be slow to reflect market realities. Some funds may not fully account for borrower difficulties in their assessments, leading to overinflated valuations. This lack of transparency can obscure true risk levels, leaving investors with an incomplete picture of their exposure.
Property construction loans: a high-risk sector
Within private credit, property construction loans present additional uncertainties. These loans carry heightened risk due to potential project delays, cost overruns, and regulatory challenges. If a developer runs into trouble, repaying loans can become difficult, increasing default risk. Investors need to be particularly cautious, as construction loan liquidity is often low, making early exits difficult and potentially costly.
A stabilising force amid high yield credit volatility
To offset the unpredictability of high yield credit, government bonds can provide a stabilising force. While rising interest rates have made some existing bonds less attractive, new issuances offer higher yields, improving their appeal. As inflation moderates and rates decline, Australian government bonds are likely to benefit, offering stability and capital appreciation with expected rate cuts and price gains over the next 24 months. These assets serve as a crucial counterweight in diversified portfolios, helping to manage risk while ensuring a steady income stream.
Additionally, bonds rated AAA are considered to be of the highest quality and are associated with the lowest level of risk. They are often issued by governments with strong and stable economies, excellent credit histories, and a very low probability of defaulting on their debt obligations.
Top of the stack: What seniority means for bondholders
Striking the right balance
The key to navigating fixed income investing is striking the right balance. High yield credit funds can play a role in generating returns, but they should not dominate an investment portfolio. Instead, blending high yield opportunities with more stable assets—such as government bonds—can create a more resilient approach. Investors who focus solely on high returns without accounting for risk may find themselves exposed to hidden dangers when markets shift.
By understanding the underlying risks and ensuring diversification, investors can build a portfolio that maximises opportunity while safeguarding against unforeseen challenges. In today’s dynamic market, getting the balance right is the key to long term success.
This information is for professional and wholesale investors only and has been prepared by JamiesonCooteBonds Pty Ltd ACN 165 890 282 AFSL 459018 (‘JCB’). Channel Investment Management Limited ACN 163 234 240 AFSL 439007 (‘CIML’) is the Responsible Entity and issuer of units for the CC JCB Active Bond Fund ARSN 610 435 302, CC JCB Global Bond Fund ARSN 631 235 553 and the CC JCB Dynamic Alpha Fund ARSN 637 628 918 (collectively ‘the Funds’). Channel Capital Pty Ltd ACN 162 591 568 AR No. 001274413 (‘Channel’) provides investment infrastructure and distribution services for JCB and is the holding company of CIML.
This information is supplied on the following conditions which are expressly accepted and agreed to by each interested party (‘Recipient’). This information contains general financial product advice only and has been prepared without taking into account the objectives, financial situation or needs of any particular person. It is intended solely for wholesale clients (including sophisticated investors) as defined under sections 761G and 761GA of the Corporations Act 2001 (Cth). JCB is not licensed in Australia to provide financial product advice or other financial services to retail investors.
The information provided should not be considered personal advice, a recommendation, or an offer to invest in the Funds. Recipients should not rely on this information in making investment decisions. A Recipient should, before making any investment decisions, consider the appropriateness of the information, and seek professional advice.
Neither JCB, Channel, CIML or their representatives and respective employees or officers (collectively, ‘the Beneficiaries’) make any representation or warranty, express or implied, as to accuracy, reliability or completeness of this information or subsequently provided to the Recipient or its advisers by any of the Beneficiaries, including, without limitation, any historical financial information, the estimates and projections and any other financial information derived there from, and nothing contained in this information is, or shall be relied upon, as a promise or representation, whether as to the past or the future. All investments contain risk. Past performance is not a reliable indicator of future performance.
For further information and before investing, please read the Product Disclosure Statement and Target Market Determination which is available from www.channelcapital.com.au
Thank you for sharing your feedback.
Oops! Something went wrong while submitting the form.
Perspective, not prediction.
Timely views from the investment team on policy, market structure and portfolio construction.